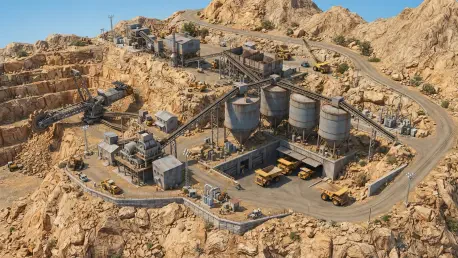
While property rates in the India, Middle East, and Africa region dropped by 19%, the cost to protect mines from civil unrest has reached unprecedented heights. This sharp divergence reflects a deepening crisis in the African mining sector, where political volatility has evolved from a manageable operating cost into a decisive factor for project viability. In the current climate of 2026, the Democratic Republic of Congo and its neighboring regions are witnessing a fundamental shift in how international investors and lenders perceive security. As conflict lines shift and social unrest becomes more frequent, the traditional financial models used for massive resource extraction are being tested by the sheer scarcity of affordable insurance. This is not merely a matter of rising premiums; it is an existential challenge for the industry as the availability of high-limit coverage begins to dry up, potentially halting the development of essential mineral resources that are critical for global industrial growth and the green energy transition.
The Financial Impact of Regional Instability
Measuring the Volatility in the DRC
The Democratic Republic of Congo serves as a stark example of how rapidly security deterioration can inflate operational costs for multinational mining entities. Within a single year, premiums for political violence coverage for specific operations spiked between five and tenfold, driven by the escalating conflict with rebel groups in the eastern provinces and significant anti-government unrest in Kinshasa. This surge forced major players such as Glencore and CMOC Group to operate in a hyper-expensive environment where the cost of protection threatened to erode the economic benefits of resource extraction. These companies are now facing a reality where political risk is no longer a secondary consideration but a primary driver of the bottom line. The volatility in the region highlights a broader trend across the continent, where the disconnect between the physical security on the ground and the financial requirements of international insurance markets is becoming wider.
Financial data from the region confirms the magnitude of this shift, with local insurers like SFA Congo seeing their political violence portfolios double in value throughout the current cycle. This increase contributed to a rise in total turnover, reaching more than $81 million as of 2026. While the Congolese insurance market has grown significantly since its liberalization—expanding to approximately $350 million in total non-life premiums today—this growth has been accompanied by extreme price volatility. The liberalization was intended to bring in more capital and lower costs, but the localized nature of the security threats has meant that capacity remains concentrated and expensive. For a mining project to remain attractive, it must now secure coverage that is not only robust but also sustainable over a multi-decade operational lease. Without such stability, the initial influx of capital during the liberalization phase may fail to support long-term infrastructure needs.
Divergence in the Global Insurance Market
A critical finding in the current landscape is the stark divergence between the general commercial insurance market and specialist risk lines in Africa. Data indicates that across the broader region, general commercial rates actually fell significantly, representing the sharpest regional decline globally. Property rates specifically dropped, reflecting an abundance of capital for routine commercial risks. This creates a paradoxical landscape: while capacity is abundant for standard business operations—driven by strong competition, surplus capital, and lower reinsurance costs—it is increasingly scarce for specialist risks like political violence, war, and complex infrastructure. This selective scarcity means that while a standard warehouse in a stable region might see falling premiums, a copper mine in a conflict zone faces astronomical costs and narrowing coverage. Investors must therefore distinguish between general market trends and the specific volatility inherent in high-stakes mining operations.
This divergence underscores a market that is highly sensitive to localized shocks, even when global capital remains relatively liquid. Specialist underwriters are becoming more surgical in their approach, carving out specific risks that they are no longer willing to cover at any price. For African mining projects, this means that the blended insurance rates often cited in global reports are increasingly irrelevant. Instead, the focus has shifted to the niche capacity available for political violence and terrorism along with political risk insurance. When these specific pools of capital contract, the impact on project finance is immediate. Even if a project is technically sound and the mineral demand is high, the inability to secure these specialist lines can stall development. The market is currently witnessing a flight to quality, where only the most well-protected and strategically significant projects can access the remaining capacity, leaving smaller ventures to face a lack of protection.
Beyond Premiums: The Capacity Equation
Understanding the Elements of Project Risk
Industry experts emphasize that the nominal price of a premium is only one part of the complex capacity equation that governs mining viability. The more pressing concern for large-scale African projects is the total amount of risk an insurer is willing to take on, known as capacity. Key components of this equation include coverage limits, which define the maximum amount an insurer will pay for a loss. If the limit is lower than the project’s total value, the investor must retain the remaining risk on their own balance sheet. Furthermore, deductibles have become a major hurdle; as risks rise, insurers often demand higher out-of-pocket costs from the investor before coverage kicks in. This effectively shifts the financial burden back to the company, making the insurance policy a less effective tool for risk transfer. When these terms are adjusted unfavorably, even a project with a secured premium can become economically unattractive or fail to meet safety requirements.
The tenor or duration of the coverage is another critical element that is currently under pressure. Long-term mining projects, which often span twenty to thirty years, require insurance continuity to satisfy lenders. However, political violence insurance is frequently subject to volatile annual renewals, creating a mismatch between the project lifecycle and its financial protection. If an insurer refuses to offer a long-term commitment or introduces narrower policy language that excludes high-probability risks like localized civil unrest, the project risk profile changes overnight. This uncertainty transforms insurance from a routine administrative expenditure into a definitive financing constraint. Investors are now finding that the ability to secure long-term, high-limit capacity is just as important as the quality of the ore itself. Without guaranteed protection over the full duration of a mining lease, the capital-intensive nature of these ventures makes them difficult to justify.
Insurance as a Constraint on Project Financing
Securing capital for massive infrastructure and mining ventures is almost always contingent upon obtaining specific insurance protections. When capacity contracts, projects may fail to reach financial close because the gaps in coverage make the venture too risky for banks to fund. In the Democratic Republic of Congo, even when localized security appears to stabilize, the underlying fear is that the necessary protection will not be available for the full lifecycle of a lease. This creates a persistent barrier to growth, as lenders require certainty that their capital is shielded from the unpredictable nature of political upheaval. When insurance capacity shrinks, sponsors are often forced to provide additional capital to cover the gaps or accept tighter, more expensive conditions from financial institutions. This dynamic has turned insurance underwriters into unintended gatekeepers of the continent’s industrial development, as their risk appetite dictates which projects move forward.
To address this capacity gap, multilateral institutions are stepping in to bolster the risk-transfer architecture of the continent. A notable development is the significant equity investment by regional development banks into trade and investment insurance entities. This move is designed to strengthen the capital base of these organizations, allowing them to provide more robust political risk and credit insurance products. By moving risk away from individual investors and private lenders, these multilateral interventions aim to facilitate the flow of private capital into high-growth but high-risk sectors. This support is essential for maintaining the momentum of African infrastructure development, as it provides a safety net that private markets currently struggle to offer independently. The success of these initiatives will determine whether the mining sector can continue to attract the massive investments needed to meet the global demand for transition minerals in the coming years.
Reducing Exposure through Data and Engineering
The industry responded to these challenges by shifting its focus toward a more integrated approach to risk management during the early planning stages. Project sponsors increasingly treated insurance as a foundational element of design rather than a final administrative hurdle. By engaging brokers and underwriters before the financing packages were finalized, companies ensured that insurance terms aligned with the stringent expectations of international lenders. This proactive strategy allowed for better financial modeling, helping firms avoid the sticker shock of sudden premium spikes that previously derailed projects during their final approval phases. Furthermore, the role of multilateral institutions became central to the risk-transfer architecture. Their strategic equity investments in regional agencies helped absorb the volatility that private markets found too difficult to handle alone, providing a necessary safety net that maintained the flow of foreign direct investment.
Beyond financial instruments, mining entities focused on primary risk reduction through advanced engineering and physical security measures. Improving the transparency and quality of underwriting data was a vital step that allowed insurers to price risks more accurately. By providing granular information regarding security incidents and project performance, companies reduced the ambiguity that often led to prohibitive premiums. This data-driven approach, combined with resilient infrastructure design, helped lower the overall exposure of critical assets in conflict-prone areas. Ultimately, the viability of major projects depended on this evolution toward more sophisticated risk-reduction strategies. The industry moved away from relying solely on short-term price relief and instead focused on securing long-term capacity. These measures collectively ensured that the essential mineral resources required for the global economy remained accessible, despite the ongoing political challenges.