The synthesis of judicial reasoning in the Vivid Housing case suggests that interim safety measures like fire patrols satisfy the requirement for immediate action. Property owners across the United Kingdom and internationally have watched the proceedings of Vivid Housing v Allianz Global Corporate & Specialty with bated breath, as the decision fundamentally reshapes the legal landscape of building insurance. For years, the ambiguity surrounding the term “imminent threat” allowed insurers to sidestep liability for latent construction defects that posed significant safety risks but had not yet resulted in a physical catastrophe. The case centers on Collins Place, a 72-flat development where combustible cladding and missing fire barriers created a perilous environment. This ruling represents a departure from literalist interpretations that required a fire to be practically occurring before coverage could be triggered, favoring instead a common-sense approach to structural risk and life safety.
Defining the Core Conflict: Structural Integrity Versus Temporal Imminence
At the heart of this legal battle lies the question of how to quantify the danger posed by structural failures that remain dormant until a triggering event occurs. The Collins Place development in Portsmouth served as the primary case study, highlighting a series of critical fire-safety flaws discovered just days before the expiration of a long-term insurance policy. While certain materials were categorized as a medium risk, the absolute absence of proper fire compartmentation and cavity barriers was flagged as a maximum-priority hazard. These defects meant that in the event of any small ignition, the entire building could be engulfed in flames with terrifying speed, leaving residents with virtually no time to evacuate safely. The insurer, Allianz, argued that because no fire had occurred within the policy period, the threat remained theoretical rather than imminent. This stance forced a judicial inquiry into whether the physical state of the building itself could constitute a trigger for remedial claims.
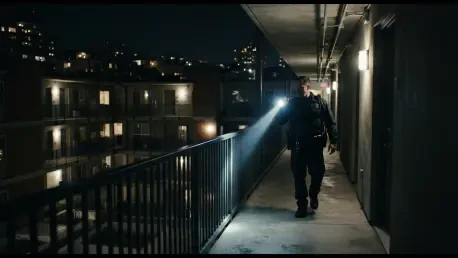
To mitigate the life-safety risks identified by professional surveyors, Vivid Housing implemented a “waking watch,” which involved 24-hour patrols by trained personnel to monitor for smoke and heat. This measure is common in buildings with known cladding issues, yet it sparked a significant debate over the definition of “immediate remedial action” required by insurance policies. Allianz contended that the decision to hire guards rather than begin an immediate, permanent reconstruction proved that the threat was not truly urgent. They maintained that for a threat to be imminent, the damage must be virtually certain to occur within hours or days of the discovery. However, the housing association argued that the necessity of a waking watch was, in itself, proof of an immediate safety crisis. The financial burden of such interim measures can be staggering, often reaching thousands of pounds per week, further complicating the relationship between policyholders and their insurance providers in this sector.
The Judicial Shift: Moving Beyond Literalism in Insurance Terms
The High Court initially faced a request from Allianz for a summary judgment to dismiss the claim without a full trial, a maneuver often used to resolve clear-cut contractual disputes quickly. The insurer’s defense rested on a narrow, dictionary-based reading of the words “imminent” and “immediate,” suggesting that the policy wording created an exceptionally high bar for coverage. Mrs. Justice Jefford rejected this rigid interpretation, concluding that the housing association had a realistic prospect of proving its case based on the severity of the structural failures. Allianz subsequently appealed, claiming that the High Court had effectively rendered the specific wording of the policy meaningless by treating any serious fire-safety defect as an automatic trigger for insurance payouts. This appeal forced the higher courts to weigh in on the balance between contractual precision and the practical realities of managing large-scale residential safety risks in an era characterized by a heightened level of regulatory scrutiny.
In a unanimous decision, the Court of Appeal upheld the earlier ruling, providing a robust definition of what it means for a threat to be truly imminent in a modern construction context. Lord Justice Stuart-Smith emphasized that “imminent” does not strictly mean “on the verge of happening” in a chronological sense. Instead, the court looked to precedents establishing that a threat is imminent if it is sufficiently serious and the consequences are likely to be catastrophic if the defect is not rectified. The court recognized that structural defects in high-rise buildings create a constant state of danger that does not reset every day a fire fails to break out. By rejecting the insurer’s attempt to use the absence of a disaster as a shield, the judiciary has lowered the evidentiary hurdle for policyholders. This shift acknowledges that the remedial steps mentioned in insurance policies can include necessary interim safety protocols designed to prevent loss of life while permanent solutions are being engineered.
Future Implications: Strengthening the Framework for Building Safety
This landmark ruling coincides with a broader legislative push to address the systemic failures of the construction and insurance sectors. Current regulations, such as the Building Safety Bill, have introduced stringent duties for building owners to ensure the safety of their structures, with substantial penalties for non-compliance. In the landscape of 2026, the intersection of judicial clarity and legislative rigor has created a more predictable environment for property managers who must navigate the complexities of legacy cladding issues. The ruling in the Vivid Housing case serves as a powerful reminder that insurance policies are intended to provide protection against substantial risks, not just to act as a reactive mechanism after a tragedy has occurred. Insurers are now under increased pressure to conduct thorough risk assessments and to recognize that structural instability and fire-pathway failures are objective hazards that require timely financial interventions rather than prolonged legal challenges over semantics.
The final consensus of the court established that the threat of damage was best evaluated through an objective lens rather than a restrictive timeline. Building owners were encouraged to document all structural surveys with high precision, ensuring that red-priority risks were clearly identified by independent experts before policy expiration dates. It was determined that proactive mitigation, such as the implementation of fire patrols, served as valid evidence of the immediate need for remedial action. Stakeholders in the construction industry adjusted their risk management strategies to align with these findings, prioritizing the removal of combustible materials through a combination of insurance claims and direct developer liability. For those managing residential portfolios, the primary takeaway focused on the necessity of comprehensive data gathering and the aggressive pursuit of coverage for latent defects. Moving forward, the insurance industry faced a requirement to modernize policy language to reflect these safety realities.