The thin line between a protected business asset and an excluded luxury item often remains invisible until a catastrophic event forces a microscopic examination of insurance policy verbiage. For E.J. Sutton, a Utah-based entrepreneur specializing in the delicate transport of taxidermy, this realization arrived during a violent windstorm in Montana that upended his trailer and scattered his high-value cargo across the highway. Although he had secured a policy with Progressive Insurance providing $200,000 in cargo coverage, the insurer’s subsequent denial of the majority of his claim sparked an intense debate over the nature of his cargo. The central dispute hinges on whether preserved animal specimens should be classified as rated commodities like skins and furs, which were explicitly listed in his paperwork, or as artwork, a category specifically excluded from his coverage. This semantic disagreement has left a professional transporter facing a devastating financial loss during a period of significant economic uncertainty.
Navigating the Semantic Divide and Ensuring Future Protection
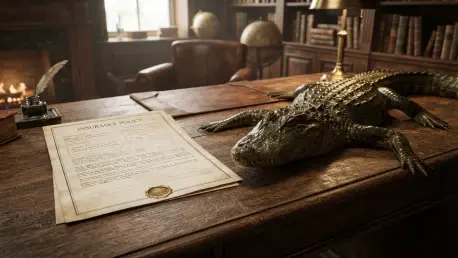
When the storm winds pushed Sutton’s trailer off the road, the resulting damage to the mounted animals was extensive, involving thousands of dollars in restoration or total replacement costs. Sutton believed the language of his policy, which specifically included skins, furs, and textiles as rated commodities, provided the necessary safety net for his specialized operations. However, Progressive Insurance interpreted the finished taxidermy pieces not as raw animal products but as completed artwork, a distinction that triggered a restrictive exclusion clause within the fine print of the contract. This classification effectively stripped the transport business of its expected financial protection, leaving the owner to grapple with the reality that his primary revenue source was essentially uninsurable under his current plan. While the insurer issued a minimal payment of roughly $437 for a damaged alligator rug, the far more valuable items, including a fully mounted mountain lion, were denied as artwork.
This incident underscores a persistent and systemic challenge within the insurance industry known as the coverage gap, where the perceptions of the policyholder and the legal definitions of the insurer fail to align. Sutton expressed a profound sense of being misled, as he had specifically sought out coverage that would protect his taxidermy transport business from the very risks he encountered on that Montana road. The discrepancy suggests that even when a professional provides a clear description of their business activities, the internal coding and categorical exclusions used by major carriers can lead to unexpected denials. Progressive Insurance has remained largely silent on the specifics of the case, citing privacy concerns regarding individual customer claims, which leaves other business owners in similar industries wondering about the stability of their own policies. The situation serves as a stark reminder that the inclusion of certain keywords in a policy does not always guarantee protection.
Business owners in niche sectors recognized that standard cargo policies often contained hidden pitfalls that required professional scrutiny before any shipment commenced. To mitigate these risks, industry experts recommended that transporters provide exhaustive, written descriptions of their cargo to agents and demand explicit confirmation that no exclusions applied to those specific items. It was determined that verbal assurances were insufficient, as the written contract remained the final authority during the claims process. Professionals sought out specialized brokers who understood the nuances of unique commodities, ensuring that terms like artwork were clearly defined or waived in relation to taxidermy. They also maintained detailed logs of all correspondence and requested formal endorsements to override standard exclusions that might jeopardize their operations. This proactive approach allowed entrepreneurs to bridge the coverage gap by securing ironclad agreements to ensure their long-term stability.