The anticipated 2027 renewal season is expected to bring significant rate relief for regional cedants due to a persistent lack of major claims activity across major Asian economies. This transition comes at a moment when global markets have traditionally faced tightening conditions, yet the Asia Pacific corridor remains a distinct outlier characterized by structural stability and a surplus of underwriting capacity. Major global reinsurers continue to view the region as a primary growth engine, largely because the fundamental trade flows and industrial activities have not been disrupted by the same scale of catastrophic losses witnessed in Western territories. While inflationary pressures have inevitably pushed up the total value of insured assets and the complexity of underlying exposures, the competitive landscape has largely prevented these rising costs from translating into higher premiums. Instead, the market is experiencing a convergence of high capital availability and favorable historical performance, which naturally tilts the bargaining power back toward regional insurers as they prepare for upcoming negotiations.
Market Dynamics: The Intersection of Capital and Exposure
The current surplus of capital in the region is largely driven by a strategic pivot among the world’s largest reinsurers, including Swiss Re, Munich Re, Scor, and Hannover Re, all of whom have maintained a strong presence in the East. Unlike the “hard” market conditions recently prevalent in London and European hubs, where capacity retrenchment followed years of poor underwriting results, the Asia Pacific marine and energy sectors have benefited from a more disciplined yet abundant supply of coverage. This creates a soft pricing environment that effectively counters the rising costs associated with global supply chain complexities and increased vessel values. Brokers are now finding themselves in a unique position to leverage this oversupply, ensuring that regional clients are not penalized by global trends that do not reflect the actual risk profile of Asian territories. Consequently, the surplus acts as a buffer, allowing the local market to absorb inflationary shocks while maintaining attractive pricing structures that encourage further infrastructure investments.
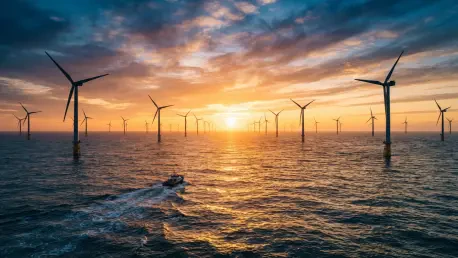
Building on this foundation of financial stability, the region’s role as a global manufacturing and energy hub continues to draw significant investment into both traditional and emerging sectors. From the expansive offshore oil and gas operations in Southeast Asia to the burgeoning offshore wind projects in the Taiwan Strait, the diversity of risks requires a sophisticated approach to capital allocation. Reinsurers are increasingly willing to offer broader terms for these high-value assets because the underlying economic fundamentals remain exceptionally strong. This willingness is not merely a matter of tactical competition but a calculated response to the persistent demand for insurance in a region that accounts for a massive portion of global trade volume. As trade lanes remain active and new energy projects come online through 2027, the demand for reinsurance will naturally grow, but the current trajectory suggests that the supply of capital will continue to outpace this demand, keeping the downward pressure on rates firmly in place for most standard commercial risks.
Strategic Outlook: Managing Volatility and Emerging Risks
One of the most compelling factors supporting the downward trend in reinsurance rates is the remarkable absence of major catastrophic losses over the last few years. While minor incidents occurred in Korea during the early part of the decade, the primary economic engines of China and Japan have largely avoided the devastating storms and industrial accidents that typically trigger large-scale marine or energy claims. This lack of volatility has been a key differentiator for brokers when negotiating with global reinsurers, allowing them to isolate the Asia Pacific book of business from the more volatile global portfolios. By highlighting this consistent performance, intermediaries have successfully argued for favorable pricing in “vanilla” lines such as marine hull, cargo, and upstream energy. This historical stability provides a solid baseline for the 2027 renewals, suggesting that unless a major unforeseen disaster occurs, the narrative of a soft market will remain dominant, providing regional insurers with the fiscal space to expand their own product offerings.
Looking ahead, the industry shifted its focus toward the complexities of the renewable energy sector and the potential disruptions brought by the AI technology revolution. Market participants realized that while traditional marine and energy lines remained stable, the integration of artificial intelligence introduced novel exposure types that required proactive risk assessment. Experts suggested that cedants utilized this period of lower rates to reinvest in advanced data analytics and bespoke modeling for renewable projects, such as offshore wind farms, which faced more intricate risk profiles than fossil fuel assets. Reinsurers encouraged a move toward more granular underwriting to prepare for the possibility of large-scale technological losses that could emerge as the manufacturing sector automated further. By the time the 2027 cycle concluded, the most successful firms had already established clear frameworks for identifying these emerging threats, ensuring they remained resilient against future volatility. This stance allowed the regional market to maintain its edge.