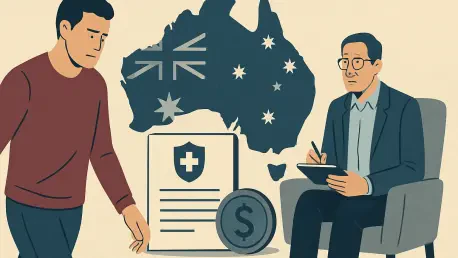
Mental health-related disability claims now account for one-third of all total and permanent disability payouts across the Australian insurance sector. This financial shift reflects a growing crisis in clinical retention, where nearly half of all men who initiate mental health treatment discontinue their care prematurely. A 45% dropout rate among male patients represents more than just a healthcare hurdle; it serves as a primary driver of escalating costs for life insurers and workers’ compensation frameworks. When a patient exits therapy before achieving clinical stability, the underlying condition often worsens, leading to extended claim durations and a significantly reduced probability of a successful return to the labor market. This lack of continuity transforms manageable psychological episodes into long-term liabilities that threaten the structural integrity of group insurance portfolios. The ripple effect is felt nationwide as insurers struggle to balance rising claim volumes against the need for affordable premiums.
Financial Implications of Untreated Psychological Distress
The financial data regarding these claims highlights a system under extreme pressure, with mental health payouts reaching a staggering $2.2 billion annually as of 2026. Over the last five years, these costs have effectively doubled, creating a precarious environment for major insurers who must now account for a massive volume of claims that were previously statistically rare. Perhaps most alarming is the 700% surge in mental health-related Total and Permanent Disability claims among workers in their 30s. As the claims-to-premium ratio climbs toward 91%, insurance providers are discovering that the cost of providing coverage is rapidly catching up to the income generated by premiums. This narrowing margin threatens the long-term sustainability of group insurance portfolios, forcing a re-evaluation of risk assessment models. Without a change in how these cases are managed, the economic foundation of the national insurance sector remains at a high risk of collapse.
The disparity between physical and psychological recovery further complicates the insurance landscape, as the return-to-work gap continues to widen for those suffering from mental health issues. While most workers successfully return to their jobs following a physical injury, those with psychological injuries face a much lower success rate, falling to approximately 76% in recent years. These claims are also disproportionately expensive, carrying a median cost of over $58,000, which is more than three times the cost of a standard physical injury claim. Because men who drop out of therapy are at a significantly higher risk for deteriorating conditions and repeat claims, their absence from work lasts nearly four times longer than the national average for other injuries. This extended period of inactivity creates a cycle of dependency on insurance payouts that drained resources and prevented individuals from regaining their professional roles or financial independence.
Reimagining Clinical Engagement for the Male Demographic
The reasons men disengage from treatment often stem from a fundamental mismatch between traditional therapeutic models and male communication styles. Statistics show that 87% of Australian men who died by suicide had actually interacted with a healthcare service in the year prior, suggesting that while men are reaching out, the system is failing to keep them engaged. Experts argue that many clinical settings are not optimized for how men experience or express emotional distress, leading to feelings of alienation or inadequacy during the therapeutic process. This clinical gap prevents the formation of a strong therapeutic alliance, which is the most reliable predictor of whether a patient will stay in treatment or abandon it. When the clinician fails to build this bond, the patient is likely to view the sessions as unproductive, leading to a high dropout rate that ultimately increases the burden on insurers who must manage the resulting long-term disability outcomes.
To address this engagement crisis, organizations such as Movember and Bupa are championing specialized clinician training to bridge the gender gap in mental health care. Programs like Men in Mind focus on teaching therapists how to better connect with male patients, emphasizing action-oriented strategies and communication techniques that resonate more effectively with men. By increasing clinician confidence and tailoring the therapeutic approach to be more gender-responsive, the industry aims to drastically reduce the dropout rate. Early results suggest that when the therapy is adapted to the patient’s specific needs, men are far more likely to complete their treatment and successfully return to work. This targeted intervention not only improves the individual’s quality of life but also serves as a strategic tool for insurers to reduce claim durations and lower the overall financial impact of psychological injuries within the workforce and broader insurance market.
Shifting Industry Paradigms and Regulatory Responsibility
In response to these rising costs, the insurance industry is shifting its philosophy from simple income replacement to active intervention. Major claims managers and insurers are beginning to realize that providing financial support alone does not facilitate recovery; in fact, psychological claims have risen over 400% in the last few years under the old model. The new strategy prioritizes rehabilitation over cash payouts, mandating specific treatment pathways and investing millions into mental health access centers. By focusing on early intervention—even targeting youth through sports-based programs like the AFL’s Ahead of the Game—insurers aim to address mental health issues before they become permanent disabilities. This proactive stance marks a departure from the reactive policies of the past, focusing instead on building psychological resilience. The goal is to create a more sustainable model where insurance acts as a bridge to recovery rather than just a financial safety net.
This shift also places new responsibilities on employers and insurance brokers to manage hidden risks within the workforce. Because men utilize psychological services at a much lower rate than women, many male workers may be suffering in silence until a crisis occurs. New regulatory requirements, such as psychosocial hazard codes of practice, now legally obligate employers to identify and mitigate mental health risks in the workplace. With mental health-related absenteeism and presenteeism costing Australian businesses an estimated $6 billion annually, the move toward proactive, gender-specific intervention is becoming an economic necessity. Companies that fail to adapt to these regulations face significant legal exposure and higher insurance premiums. Consequently, the integration of mental health support into the standard workplace safety framework has become a top priority for corporate leaders who recognize the direct link between employee wellbeing and financial performance.
Strategic Steps for Sustainable Mental Health Outcomes
The strategy for stabilizing the Australian insurance sector successfully transitioned toward more personalized and gender-aware mental health interventions. Stakeholders recognized that reducing male therapy dropout was the most effective lever for controlling total and permanent disability costs. Insurers prioritized funding for clinician training and rehabilitation centers that utilized male-centric engagement models, which resulted in a notable decline in long-term claims. Furthermore, the implementation of rigorous psychosocial risk management within workplaces became a standard operational requirement, rather than an optional benefit. This proactive environment encouraged men to seek help earlier and remain in treatment longer, ultimately fostering a more resilient workforce. Future efforts continued to focus on the expansion of digital health tools and early-access programs to ensure that financial assistance remained secondary to clinical recovery. These actions collectively established a sustainable path forward for the insurance and mental health industries.