A seemingly minor administrative shift in insurance definitions can trigger a financial catastrophe capable of dismantling even the most established agricultural supply chains. The professional negligence case of Camstar Herbs Limited versus Advisory Insurance Brokers serves as a pivotal study in the fiduciary duties of intermediaries. This dispute underscores the perilous divide between technical policy wording and the operational realities of complex businesses. The litigation centered on a transition from “Gross Revenue” to “Gross Profit” coverage, a change that ultimately left a million-pound indemnity gap during a period of crisis. Understanding this failure is essential for any professional navigating the nuances of commercial risk management as we move through 2026 and beyond.
The central theme of this research focuses on the “duty of care” owed by insurance brokers when managing policy renewals and structural changes. Specifically, it examines how a failure to account for the unique supply chain dependencies of an agricultural processor led to a massive professional liability. As companies face increasing volatility, the role of the broker transitions from a mere transactional facilitator to a critical risk advisor. This case highlights the high stakes involved when a broker prioritizes modest premium savings over technical suitability, questioning the standards of a “reasonably competent broker” in complex commercial environments.
Background of the Camstar Herbs Litigation and its Industrial Significance
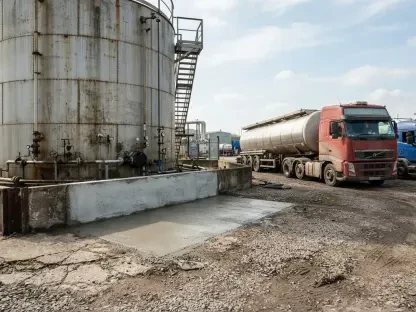
Camstar Herbs Limited stands as a dominant force in the global agricultural sector, recognized as the largest producer of dried parsley outside of China. Its operations in Suffolk rely on a delicate and symbiotic relationship with a network of external growers. The company operates a sophisticated supply chain where the processing facility acts as the vital link between the field and the final market. When a major fire decimated the primary processing plant in 2021, the company faced a catastrophic disruption mid-harvest. The operational impact was immediate, as the facility processed the vast majority of the harvested crop, and its loss threatened to bankrupt the growers who supported the business.
To prevent the total collapse of this supply chain, the CEO made the strategic decision to pay growers approximately £1.25 million for crops that could not be processed due to the fire. This research is vital because it exposes the “Gross Profit trap” within the insurance market, illustrating the devastating consequences of technical errors. The broader relevance lies in its warning to the insurance industry regarding the definition of risk. Professional negligence extends far beyond simple administrative errors; it encompasses a fundamental failure to understand how a client’s business survives a disaster. In this instance, a saving of a mere £7,000 in annual premiums resulted in a million-pound exposure that nearly ended a leading agricultural firm.
Methodology
The research is based on an exhaustive analysis of the London Circuit Commercial Court proceedings that concluded in October 2026. The methodology involved a deep dive into the technical definitions of Business Interruption (BI) insurance and a review of the brokerage’s recommendation letters dating back to the 2018 renewal period. Investigators examined expert witness testimony, specifically focusing on the scrutiny of “Increased Cost of Working” (ICW) provisions and how they apply to raw material inputs. The research compared insurance-specific accounting definitions against standard commercial accounting practices to identify where the professional advice diverged from the client’s actual needs.
Furthermore, the methodology included an evaluation of the correspondence between the broker and the insurer, Aviva, to determine the intent behind the policy change. By analyzing the “Gross Revenue” policies previously held by Camstar and comparing them to the “Gross Profit” structure implemented in 2018, researchers were able to pinpoint the exact moment the coverage became inadequate. This technical audit was supplemented by a review of the business continuity plans presented during the trial, which allowed for a clear assessment of whether the broker had fulfilled its independent professional duty to identify and mitigate core operational risks.
Findings
The court determined that the broker was negligent for failing to explain the significant implications of transitioning from a “Gross Revenue” policy to a “Gross Profit” policy. Under the new structure, raw material purchases were classified as “Uninsured Working Expenses,” meaning the substantial payments made to parsley growers were entirely excluded from coverage. One of the most damning findings was that the broker’s recommendation letter was misleading; it suggested that the client would receive identical protection for a lower price while failing to mention that the cost of the raw parsley was no longer insured. This omission directly led to the massive indemnity gap that surfaced following the fire.
Moreover, the court rejected the broker’s defense that the client’s internal business continuity plan was insufficient or that the payments to growers were purely voluntary. The judge ruled that an insurance broker has an independent professional duty to provide competent advice that is not contingent upon the client’s own internal sophistication. An attempt to claim the losses under the “Increased Cost of Working” provision was also dismissed by the court. The ruling clarified that these payments represented standard purchase costs rather than extraordinary expenses incurred to maintain turnover. Expert testimony even highlighted that such payments were a prerequisite for business survival, not an optional strategic maneuver.
Implications
The findings have significant practical implications for the insurance brokerage industry, especially for firms dealing with manufacturing and agriculture. It reinforces the legal precedent that brokers must bridge the gap between technical jargon and a client’s specific business model. For businesses with high variable costs or a heavy reliance on raw material inputs, “Gross Revenue” cover remains the only appropriate solution to ensure that the total turnover is protected. This case serves as a definitive warning that brokers cannot hide behind a client’s perceived lack of expertise to excuse a failure to identify and explain core risks during the renewal process.
Furthermore, the judgment emphasizes the danger of “premium chasing” at the expense of technical accuracy. In the current economic climate, the pressure to reduce costs is intense, yet this case proves that a small saving can lead to total financial exposure. Insurance professionals must prioritize a comprehensive coverage audit over simple price comparisons. For the wider business community, the case highlights the necessity of demanding clear, written explanations of how policy changes affect the fundamental accounting categories of their insurance. This shift toward greater transparency is expected to redefine broker-client relationships from 2026 to 2030.
Reflection and Future Directions
Reflection
The litigation highlights the high stakes of “good faith” business decisions made during a crisis. Camstar’s decision to pay its growers saved the company’s future but exposed a fatal flaw in its insurance structure that would have otherwise remained hidden. A major challenge in this research was reconciling the broker’s argument that the payments were a voluntary business choice. However, the court correctly identified that these payments were essential for the survival of the enterprise. This case study could be expanded by looking at how modern risk-assessment tools might have flagged the “Uninsured Working Expense” discrepancy before the fire occurred.
Future Directions
Future research should investigate the potential for global standardization of “Gross Profit” definitions within the insurance market to reduce linguistic ambiguity that plagues the industry. There is an urgent need to explore the evolving legal definition of “Increased Cost of Working” as supply chain volatility becomes more frequent due to climate and geopolitical factors. Further studies could examine whether mandatory disclosure checklists—specifically regarding the exclusion of raw material costs—could prevent similar professional negligence claims. From 2026 onward, the integration of automated policy comparison tools may provide a secondary layer of protection against human error in brokerage firms.
Conclusion: Lessons from the Million-Pound Oversight
The judgment against Advisory Insurance Brokers proved that the pursuit of lower premiums was an insufficient justification for eroding essential coverage. This outcome highlighted the necessity for a more rigorous standardization of insurance terminology to prevent technical oversights that lead to ruinous litigation. The case provided a clear lesson that professional duty was not a passive obligation but an active requirement to understand the granular details of a client’s cash flow. It compelled the industry to reconsider how “Gross Profit” was communicated to non-experts, ensuring that the term was no longer a source of confusion.
Ultimately, the court’s decision established that the true value of a broker was found in their ability to translate complex liability risks into resilient operational safeguards. It offered a roadmap for future professional conduct, emphasizing that transparency and technical accuracy must always outweigh the short-term goal of premium reduction. By holding the broker liable for the full £1.25 million, the legal system sent a powerful message about the cost of professional failure. This ruling served as a definitive perspective for the industry, asserting that in the world of commercial insurance, the cheapest policy was often the most expensive mistake a company could make.