A breach clock did not start ticking when malware landed; it started the moment an insurer compared the security posture that was promised on an application with the controls that actually governed identities, endpoints, and backups across production systems. Cyber insurance has changed fast,
Sticker shock hit before the open house even started, because the first number many novices now check is not list price but the annual premium that shadows it at closing—and at $2,966 on average this year, that shadow grew long enough to change dreams, budgets, and zip codes. For one Tampa couple,
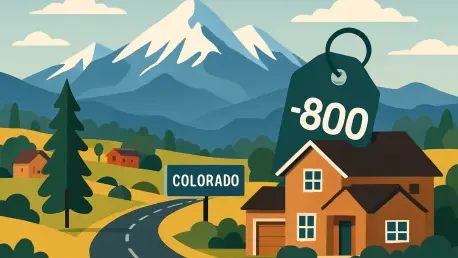
Coloradans facing relentless premium notices saw a concrete target this week: an average $800 reduction in annual homeowners insurance costs paired with a plan to keep private coverage available as wildfire, hail, and severe storms intensify across the state. Governor Jared Polis, working with the
Boards did not need another wake‑up call to see how brittle digital operations could be when a single vendor outage, an AI hallucination, or a ransomware spike could cascade through underwriting, claims, and capital in hours, and that urgency has propelled chief risk officers to redraw the map of
When families measure protection not by glossy brochures but by whether cash arrived when chemo did, whether income stayed steady when layoffs hit, and whether inheritances reached the right hands without drama, the old game of selling policies for this quarter’s tally suddenly feels small. At the
Capital is not what jolts the London market today; it is the drumbeat of regulation forcing insurers to rebuild the plumbing of their businesses—data, oversight, and resilience—well before formal compliance dates arrive and before anyone has the comfort of final text. This roundup gathers