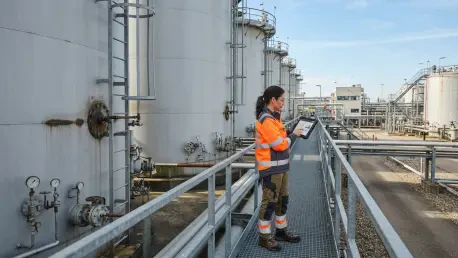
A dedicated risk engineer provides more than an audit; they develop customized service plans that address the specific operational pain points of a manufacturing facility. For middle market companies—those generating between several million and one billion dollars in annual revenue—these targeted interventions are often the only line of defense against specialized threats. These organizations occupy a precarious middle ground where they are large enough to attract significant liability but lack the internal infrastructure, such as a dedicated in-house risk manager, that larger global conglomerates take for granted. This administrative vacuum creates a critical dependency on external partnerships where the insurance carrier and broker must function as an outsourced risk management department. Without this strategic oversight, middle market firms remain highly vulnerable to volatile market shifts and complex regulatory requirements that can easily overwhelm a standard administrative team focused solely on day-to-day operations.
Navigating Legal and Industry Trends
External economic factors such as social inflation and shifting jurisdictional legal climates now play a disproportionate role in determining the success or failure of a middle market firm’s risk strategy. In highly litigious regions like Texas or Florida, the early involvement of attorneys in liability claims often causes settlement costs to skyrocket far beyond initial financial projections. Middle market firms are particularly susceptible to these inflationary pressures because they typically lack the robust legal departments and pre-negotiated settlement frameworks maintained by larger corporations. Consequently, managing risk in this environment requires a deep understanding of regional nuances and a proactive approach to claims handling to prevent manageable incidents from escalating into major financial burdens. By identifying these litigious trends early, companies can adjust their liability reserves and implement safety protocols that reduce the likelihood of legal disputes reaching a courtroom.
As businesses expand, their risk profiles become increasingly specialized based on their specific industry and geography, requiring more than a generic insurance policy. A retail chain faces a constant barrage of high-frequency general liability claims, such as slip-and-fall incidents, while a logistics company must contend with the rising severity and cost of commercial auto accidents. To address these diversities, firms are moving toward partnerships with providers that offer specialized industry verticals tailored to their operational realities. Whether a business operates in construction, healthcare, or technology, having access to an underwriting team that understands the granular exposures of that sector is essential. This specialized knowledge ensures that the coverage acts as a precise shield rather than a broad, often insufficient, safety net. This shift toward industry-specific expertise allows firms to align their insurance costs with the actual perils they face daily.
Evolution of Financial Structures and Global Reach
Growth inherently brings a shift in how a company views its financial responsibility toward risk, especially as firms move into the upper-middle segment. Many of these maturing organizations are choosing to move away from traditional guaranteed-cost insurance models toward more sophisticated loss-sensitive structures. By utilizing large deductible programs, which often range from $100,000 to $250,000, companies take an active and financially invested role in their own risk outcomes. This transition allows a business to benefit directly from its own safety successes, as lower claim frequency translates into immediate capital savings. Furthermore, these programs incentivize a culture of safety across the workforce, as the financial impact of a loss is felt directly by the organization. This evolution marks a significant milestone in a company’s corporate maturity, providing a sustainable and cost-effective path for those ready to absorb a portion of their own risk.
In today’s interconnected global economy, even mid-sized companies frequently find themselves expanding operations beyond domestic borders to capture new market opportunities. Navigating international regulations, varying local policy requirements, and complex cross-border liabilities is a daunting task for a firm that lacks a massive administrative overhead. Effective risk management for these growing firms must include a multinational strategy that provides seamless coverage across different jurisdictions. Utilizing a single carrier with an established global network simplifies the insurance program and ensures that international growth is not stalled by regulatory hurdles or unforeseen gaps in foreign coverage. This unified approach eliminates the friction caused by differing national insurance standards and provides the leadership team with the confidence to enter new territories. By securing a policy that follows them across the globe, middle market firms can compete effectively with much larger international rivals.
The Role of Consultative Risk Engineering
One of the most valuable assets available to a middle market firm in 2026 is the expertise of external risk engineers who serve as trusted advisors. In the absence of an internal safety director, these professionals provide the hands-on support necessary to identify and mitigate vulnerabilities before they result in a physical or financial loss. This consultative approach goes far beyond simple audits or checklists; it involves the creation of customized service plans that address specific operational pain points unique to the client’s facility. For instance, a logistics firm might struggle with driver safety and retention, while a manufacturer may face complex fire protection challenges in a new warehouse. By working directly with facility managers to develop and improve safety practices, risk engineers transform insurance from a reactive expense into a proactive value-multiplier. This collaborative model ensures that the firm’s physical assets and human capital are protected through expert-led mitigation strategies.
The physical location of a business often dictates the accessibility and effectiveness of these specialized risk services, making geographic footprint a primary consideration. A firm with operations spread across the Midwest, Southeast, and various Canadian hubs needs a partner capable of delivering consistent underwriting and engineering support regardless of where their facilities are situated. Recent expansions by major carriers into regional hubs like Vancouver, Calgary, and Toronto have created a more integrated North American insurance environment. This geographic synergy is particularly beneficial for cross-border operations, where a single carrier can handle exposures on both sides of the border without the gaps caused by separate policies. Having local underwriters who understand the regional market nuances while maintaining a broad North American perspective simplifies the entire insurance lifecycle. This localized yet expansive approach ensures that middle market firms receive the high-touch service they require to scale their operations securely.
Embracing Digital Transformation and Artificial Intelligence
The landscape of risk management for the middle market is currently being redefined by digital transformation, emphasizing speed and data accuracy above all else. Modern insurance platforms are streamlining the way policies are rated, quoted, and bound, which significantly reduces the administrative burden on brokers and business owners alike. Advanced technology is now being used to process vast amounts of data during the underwriting phase through a process known as submission ingestion. This allows carriers to analyze complex information from diverse sources with unprecedented speed and precision, leading to more accurate pricing and faster turnaround times. For a middle market firm, this efficiency means they can secure necessary coverage in a timeframe that matches the rapid pace of the modern market. Furthermore, the integration of these digital tools ensures that policy documents are clear, accessible, and accurately reflect the specific risks identified during the risk engineering phase.
As firms looked toward the future, the successful integration of high-tech data processing with high-touch consultative service became the hallmark of robust risk management. Leaders recognized that relying on generic coverage was no longer a viable strategy in an increasingly complex and litigious global environment. By leveraging artificial intelligence to analyze loss trends and using that data to inform localized engineering strategies, middle market companies achieved a level of sophistication previously reserved for the world’s largest conglomerates. Moving forward, businesses prioritized partnerships that offered both global reach and sector-specific expertise to ensure their insurance programs remained scalable. Taking the proactive step of auditing current environmental and professional liabilities allowed firms to close dangerous coverage gaps before they were tested by real-world claims. Ultimately, the transition toward a data-driven, service-led insurance model provided the security necessary for these firms to pursue aggressive growth objectives.