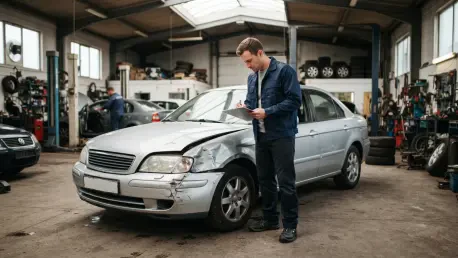
The British auto insurance market is currently navigating a period of unprecedented fiscal volatility as policyholders face the sharpest rate increases in a generation while insurers battle a surge in technical costs. This phenomenon is not an isolated event but a reflection of the broader economic pressures mounting across the United Kingdom. As the country moves through the current fiscal year, the convergence of supply chain instability and high labor costs has created a challenging environment for both underwriters and consumers.
Navigating the Volatile UK Insurance Landscape
The United Kingdom’s insurance sector is currently grappling with significant inflationary pressures that have disrupted years of relative price stability. As a cornerstone of the national economy, the auto insurance market serves as a critical indicator of broader fiscal health, reflecting the complex interplay between consumer spending, supply chain stability, and regulatory oversight. This industry is defined by its high degree of digitization, intense competition among major underwriting firms, and strict adherence to Financial Conduct Authority standards.
Recent data suggests that the sector is entering a transformative phase where rising operational costs and shifting risk profiles are forcing a fundamental reassessment of pricing strategies. Economic indicators suggest that the current volatility is part of a structural realignment. Insurers are being forced to navigate a landscape where historical data models no longer accurately predict the cost of future liabilities. Consequently, firms are recalibrating their risk appetites to ensure long-term solvency over short-term market share.
Analyzing Shifts in Consumer Behavior and Technological Integration
The auto insurance market is witnessing a rapid evolution driven by both economic necessity and technological advancement. Consumers are increasingly migrating toward digital-first platforms and comparison shopping sites to mitigate rising costs, often opting for higher deductibles or telematics-based policies to secure lower rates. These evolving behaviors are creating new opportunities for insurers to innovate with personalized, data-driven products that reward lower-risk driving patterns.
Simultaneously, the industry is adjusting to the growing prevalence of electric vehicles and advanced driver-assistance systems. While these technologies improve safety, they significantly increase the complexity and cost of vehicle repairs. This technological shift requires a workforce with specialized skills, further driving up the cost of claims. Insurers must now balance the benefits of modern safety features against the rising expense of maintaining them in a high-inflation environment.
Interpreting Market Performance Indicators and Growth Forecasts
Current market data highlights a stark divergence between headline inflation and insurance-specific cost trajectories, with auto insurance premiums outpacing general increases. While total payout figures have reached record levels, industry analysts forecast a challenging road to profitability, with net combined ratios expected to remain under pressure through 2026. This trend indicates that insurers are paying out nearly as much in claims as they are collecting in premiums, leaving little room for error.
Projections indicate that after a period of adjustment, the market may see further premium hikes of up to 12% by 2027 as insurers seek to balance their books. These growth indicators suggest a market in transition, where top-line revenue growth is currently being absorbed by the rising tide of claims inflation and administrative expenses. Investors are watching closely to see if the recent rate adjustments will be sufficient to stabilize the industry in the coming years.
Overcoming Operational and Fiscal Challenges
The primary obstacle facing the industry is the unsustainable rise in the cost of claims, which has pushed many underwriters into a deficit. Supply chain disruptions have led to a scarcity of replacement parts, while a shortage of skilled labor in the repair sector has driven up hourly rates and extended vehicle downtime. These factors combined have made the average claim significantly more expensive than it was just a few years ago.
To combat these complexities, insurers are exploring strategic solutions such as direct partnerships with parts manufacturers and the implementation of AI-driven fraud detection tools. Successfully managing these cost drivers is essential for maintaining market stability and ensuring long-term underwriting profitability. By streamlining the claims process and reducing the time a vehicle spends in the shop, insurers can mitigate some of the inflationary pressure they currently face.
The Impact of Regulatory Standards and Compliance
Regulatory bodies continue to exert significant influence over how insurers price their products and interact with customers. Recent reforms aimed at ensuring fair value and ending the loyalty penalty have forced a total overhaul of renewal pricing models. Compliance with these standards is no longer just a legal requirement but a core component of brand reputation and customer retention. Firms that fail to adapt to these transparency requirements risk significant fines and the loss of consumer trust.
Furthermore, stricter security measures regarding data protection and financial resilience are shaping industry practices. These rules require firms to maintain robust capital reserves to withstand economic shocks and potential market volatility. While these regulations provide a safety net for the economy, they also add a layer of administrative costs that must be managed. Balancing regulatory compliance with competitive pricing remains a top priority for executive leadership across the sector.
Assessing the Future Direction of the Insurance Industry
The future of auto insurance will likely be defined by a convergence of sustainability initiatives and advanced data analytics. As the United Kingdom pushes toward its net-zero targets, insurers will need to develop specialized products for the burgeoning clean energy transportation sector and address the unique risks associated with autonomous driving. This shift will require new actuarial models that can account for the different battery risks and hardware repair costs associated with cleaner energy vehicles.
Market consolidation is expected as smaller players struggle with high compliance costs and inflationary heat. Innovation in usage-based insurance and the integration of real-time risk assessment tools will likely become the standard, allowing the industry to remain agile in the face of global economic fluctuations. Firms that successfully integrate these technologies will be better positioned to offer competitive rates while maintaining healthy margins in an increasingly crowded marketplace.
Summary of Market Prospects and Strategic Recommendations
The surge in premiums proved to be a necessary response to a perfect storm of rising repair costs and broader macroeconomic volatility. To return to a sustainable footing, insurers prioritized operational efficiency and invested in technologies that streamlined the claims process. This strategic focus allowed the industry to absorb the initial shocks of the inflationary period while maintaining a high level of service for policyholders. Digital transformation became the primary tool for offsetting the rising costs of labor and materials.
Stakeholders discovered that long-term growth was inextricably tied to the successful management of social and technical inflation. Firms that maintained a transparent dialogue with policyholders regarding price adjustments while doubling down on innovation fared much better than those that resisted modernization. These actions established a blueprint for navigating future economic cycles with greater resilience. Moving forward, the industry prepared to leverage data analytics to further refine risk pricing and ensure fiscal clarity.