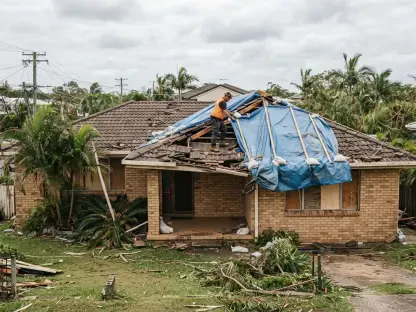
A sudden, severe weather event often leaves homeowners grappling with property damage and the complex logistics of insurance claims, making the decision of whether to share financial settlement details with roofing contractors a pivotal moment. While some industry professionals suggest that full disclosure streamlines the process by aligning the contractor’s bid with the insurance company’s approved budget, this level of transparency can inadvertently strip the homeowner of their bargaining power. By revealing the total amount of the claim upfront, the homeowner risks receiving a quote that is conveniently tailored to match the payout rather than one reflecting the actual market cost of labor and materials. In the current economic landscape, maintaining a clear separation between the insurance company’s valuation and the contractor’s independent estimate is essential for ensuring that repairs are completed at a fair price without sacrificing the quality of the final installation.
Strategic Bidding and Price Transparency
The Case for Blind Estimates
Soliciting blind estimates serves as the primary defense against inflated pricing and ensures that a contractor’s quote is rooted in the competitive reality of the local market. When a homeowner provides a roofing company with the insurance summary—including the specific dollar amounts allocated for each line item—the contractor is no longer incentivized to provide a bid based on their own internal overhead and profit margins. Instead, they often simply adopt the insurance company’s numbers, which can lead to a situation where the homeowner overpays for standard services or misses out on potential savings. By withholding these financial details, the homeowner forces the contractor to perform a thorough, independent assessment of the damage and calculate a price that reflects the actual work required. This method highlights the true cost of the project and allows for a more authentic comparison between different service providers who are competing for the job based on their merits.
Standardizing the Scope of Work
To ensure that these blind bids are useful for comparison, homeowners should provide contractors with a standardized list of required repair items derived from the adjuster’s report while keeping the approved prices hidden. This technical scope of work should include detailed specifications such as the type of shingles, the amount of flashing, and the specific underlayment materials required by the policy. Providing this information allows for an “apples-to-apples” evaluation of the proposals, making it easier to identify if a contractor is cutting corners or proposing unnecessary upgrades. This strategy also encourages a focus on the engineering requirements of the roof rather than just the total budget, leading to a more robust discussion about material durability and long-term performance. Ultimately, standardizing the project scope while maintaining price confidentiality empowers the homeowner to make a decision based on the technical accuracy and professionalism of the contractor’s proposal.
Navigating Financial and Contractual Complexity
Managing Mortgage and Escrow Requirements
Navigating the financial complexities of insurance payouts also requires a deep understanding of the administrative hurdles involved, particularly when dealing with mortgage lenders and the loss draft process. Most insurance checks for significant roof damage are issued as multi-party payments that include the mortgage servicer as a co-payee, which triggers a sequence of escrow holdings and staged fund releases. Homeowners must coordinate between the bank’s inspection requirements and the contractor’s payment schedule to ensure that work progresses without interruption. A reputable roofing company will be familiar with these requirements and will provide the necessary documentation, such as lien waivers and proof of completion, to satisfy the lender’s conditions for releasing the funds. Understanding this process prevents unexpected financial friction and ensures that the project is funded correctly while protecting the homeowner’s equity and the lender’s interest.
Distinguishing Cash Value and Replacement Costs
Understanding the nuance between Actual Cash Value and Replacement Cost Value is critical for homeowners when discussing finances with their roofing company. Most modern policies are written as replacement cost, but the insurance company does not release the full amount at once; instead, they first pay the depreciated value of the roof. The remaining balance, known as recoverable depreciation, is held back until the project is finished and a final invoice is submitted to prove the work was completed. Disclosing the total replacement value too early can lead a contractor to inflate their invoice simply to capture the maximum depreciation, even if the actual costs were lower. This practice can border on insurance fraud, making it vital for homeowners to insist on an honest billing process that reflects the real work performed. Maintaining a separate ledger of all expenses ensures that the final invoice sent to the insurance company is accurate and all funds are collected.
The effective management of an insurance claim for roof restoration requires a disciplined approach that prioritizes documentation and verifies the professional credentials of all involved parties. Property owners who maintain meticulous files—containing high-resolution before-and-after photographs, building permits, and every piece of insurance correspondence—find themselves better equipped to handle the final reconciliation of funds. It is critical to ensure that all final invoices accurately reflect the work performed to unlock recoverable depreciation and finalize the claim with the insurance carrier. This level of organization not only streamlines the immediate repair process but also serves as essential documentation for future real estate transactions, providing proof of a high-quality, code-compliant installation. By following these structured steps, homeowners can successfully navigate the intersection of insurance requirements and construction reality.