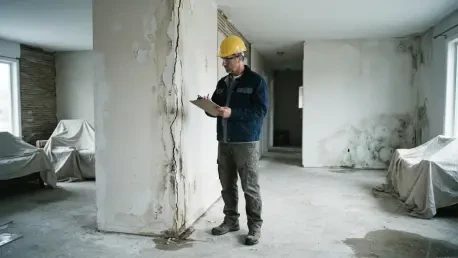
Hollard Insurance Partners admitted to multiple defaults, including delays in hiring structural engineers and providing temporary housing for policyholders in distress. This admission occurred during a critical Federal Court case that examined the insurer’s operations following its acquisition of CommInsure. The evidence presented during the hearing highlighted how a series of administrative failures left a family in Victoria in vulnerable conditions for several months. Justice Catherine Button observed that the firm’s conduct fell significantly short of industry standards, emphasizing that the duty of utmost good faith is a substantive obligation rather than a symbolic one. This judgment serves as a stern warning to the insurance sector that operational delays and poor communication carry heavy legal consequences. By failing to act with the necessary urgency, the company breached its statutory requirements, resulting in a landmark $2 million civil penalty. This case illustrates the high cost of neglect in claims handling and sets a new precedent for corporate accountability in the financial services industry.
1. Duty of Good Faith: Understanding Legal Obligations
Section 13 of the Insurance Contracts Act establishes the duty of utmost good faith as a cornerstone of consumer insurance agreements. This legal framework requires insurers to act with a high degree of fairness, honesty, and reasonableness toward their policyholders at every stage of the claims process. It is not enough for a company to simply process paperwork; it must actively consider the interests of the insured and avoid acting in a capricious or dismissive manner. In practice, failing to provide timely decisions or withholding vital information about a claim’s progress constitutes a direct breach of this implied duty. The court’s recent ruling reinforces the idea that the insurer-insured relationship is built on mutual trust, where the insurer holds a position of power that must be exercised responsibly. Consequently, any failure to maintain these standards can be classified as a statutory contravention, exposing the company to significant regulatory oversight and potential litigation.
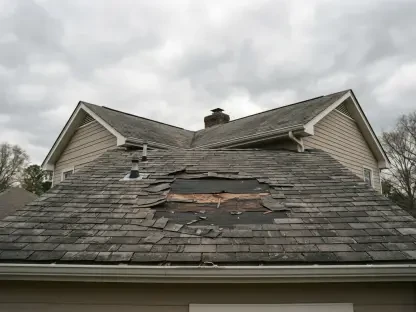
The failures identified in the current legal landscape often stem from systemic issues rather than isolated human errors. In the Hollard instance, the court noted seven distinct delays occurring between late 2026 and early 2028, reflecting a lack of urgency in processing claims. These defaults included a failure to promptly hire structural engineers and significant delays in arranging for mold remediation, which ultimately led to the total loss of a policyholder’s property. Beyond technical assessments, the insurer struggled with basic communication, failing to explain the basis of cash settlement offers or properly integrate expert findings into its decisions. Such failures demonstrate how poor internal governance and inadequate staffing can leave families in appalling living conditions while their claims remain stagnant. By ignoring industry standards, such as the General Insurance Code of Practice, companies risk not only financial penalties but also lasting damage to their professional reputation within the national financial ecosystem.
2. Financial Consequences: Calculating Civil Penalties
When the court calculates civil penalties for insurance breaches, it applies a formula based on the company’s annual revenue to ensure the fine acts as a genuine deterrent. In this specific case, the maximum potential penalty was calculated at a staggering $81.6 million, representing ten percent of the insurer’s annual revenue during the period of the contravention. Although the final fine was set at $2 million, the court intended this figure to send a clear message that the duty of utmost good faith is a mandatory legal standard. The determination factored in the severity of the claim handling failures and the prolonged duration of the defaults, which impacted the lives of actual policyholders. Justice Button noted that the penalty must be sufficient to prevent companies from treating such breaches as a mere cost of doing business. This financial consequence highlights the increasing willingness of regulators and courts to hold large financial institutions accountable for the human impact of their operational inefficiencies.
Cooperation with regulatory bodies like the Australian Securities and Investments Commission often plays a crucial role in determining the final severity of a legal penalty. The court acknowledged that Hollard cooperated fully throughout the proceedings and took proactive steps to remediate its internal systems after the breaches were identified. These improvements included reducing staff-to-claims ratios and implementing more sophisticated, integrated claims management systems designed to prevent the recurrence of such delays. By acknowledging its faults and investing in better governance, the company demonstrated a commitment to reform that the court recognized in its final judgment. However, the requirement for deterrence remained paramount, as the court sought to ensure other industry participants take their statutory duties seriously. This balance between punishment and remediation provides a roadmap for how insurers should handle regulatory scrutiny, emphasizing that early intervention and transparent cooperation are essential for mitigating long-term legal exposure.
3. Revised Standards: Integrating the Insurance Code
The evolving regulatory environment is further shaped by the Insurance Council of Australia’s recent submission of a revised General Insurance Code of Practice for approval. These updates are designed to strengthen consumer protections by ensuring that code provisions regarding trauma-informed claims handling and cash settlements are explicitly integrated into the insurance policies themselves. This change means that a failure to adhere to the code’s timeframes or communication standards would directly equate to a breach of contract, allowing policyholders to seek legal remedies and damages. The transition from industry guidelines to binding contractual obligations marks a significant shift in how claims management will be policed in the coming years. Insurers must now prepare for a landscape where regulatory compliance is not just about avoiding fines but also about fulfilling contractual promises made to every individual client. This shift reflects a broader trend toward transparency and accountability in the financial services sector.
To navigate these changes, insurance providers must adopt rigorous risk management strategies and update their internal governance protocols. This includes auditing claim decision timelines and ensuring that all communications are clear, timely, and documented with precise justifications. Companies should also establish concrete deadlines for claim resolutions that align with the revised code and enhance support systems for vulnerable policyholders or those facing financial hardship. Furthermore, it is essential to increase oversight of third-party vendors, such as structural engineers and emergency repair teams, to ensure they meet the same high standards of accountability as the primary insurer. Implementing surge capacity controls and evaluating staffing levels will also help minimize delays during peak periods or natural disasters. Finally, insurers must prioritize immediate rectification of handling mistakes and use complaint data to drive continuous improvement, ensuring that all internal dispute resolution processes are synchronized with the latest regulatory guidance.
4. Operational Oversight: Actionable Outcomes for Insurance Providers
Understanding the intricacies of the duty of utmost good faith is essential for both consumers and insurance professionals operating in today’s market. Many stakeholders ask what specifically constitutes this duty; it is a statutory mandate requiring insurers to act with honesty and reasonableness throughout the life of a policy. Another common question involves the calculation of penalties, which are determined by the severity of the breach and the company’s financial scale, often reaching up to ten percent of annual revenue. The Hollard case demonstrated that the court looks beyond technical compliance to evaluate whether the insurer considered the policyholder’s wellbeing. For instance, if an insurer delays essential repairs without a valid reason, it is essentially disregarding the policyholder’s interests, which the court views as a violation of the law. These legal definitions provide the framework for assessing whether an insurance company has met its obligations or if its actions warrant judicial intervention and substantial financial remediation.
As the industry moves forward, policyholders often inquire whether a breach of the industry code can lead to a lawsuit. Under the proposed regulatory revisions, code provisions will become enforceable parts of the insurance contract, allowing individuals to seek damages for non-compliance. This evolution underscores why the General Insurance Code of Practice is changing; it aims to offer better support during traumatic events and more transparent settlement processes. In previous years, insurers may have treated code violations as minor administrative issues, but the current legal environment treats them as serious contractual failures. Organizations that were previously slow to update their claims handling processes now face the reality of strict judicial oversight and increased consumer litigation. To stay competitive and legally compliant, firms must embrace these changes by investing in better technology and human-centric service models. Looking ahead, the focus remains on fostering a culture of accountability where the duty of good faith is practiced daily, rather than being treated as a theoretical concept.