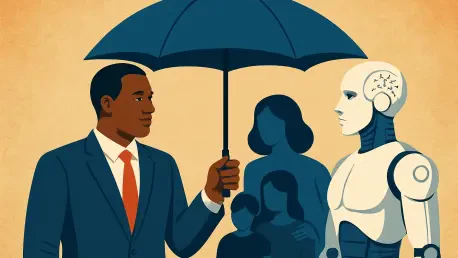
A representative sample of the insurance market is being required to disclose internal oversight mechanisms and governance for AI deployment. This significant mandate, issued by California Insurance Commissioner Ricardo Lara, signals a transformative era in the regulation of the nation’s largest insurance market. As algorithms increasingly take the lead in underwriting, pricing, and claims handling, the California Department of Insurance is taking a proactive stance to ensure that technological sophistication does not undermine established consumer protections. This initiative is designed to pull back the curtain on the “black box” of automated decision-making, requiring insurers to justify the logic behind their mathematical models. By focusing on firms that wrote a minimum of two hundred and fifty million dollars in annual premiums, the state is targeting the entities with the greatest impact on the financial well-being of its residents. The effort marks a transition from identifying theoretical risks to enforcing concrete standards for the digital age.
Establishing Core Principles for AI Governance
Prioritizing Transparency: Fairness and Privacy
At the heart of this regulatory push lies the critical need to demystify the complex mathematical models that insurers now use to evaluate risk and process claims. There is a growing concern within the California Department of Insurance that as these technologies become more sophisticated, they risk becoming opaque “black boxes” where decisions are made without any clear explanation for the consumer. When policyholders see a sudden premium increase or face a denied claim, they deserve to understand the logic behind that decision rather than being met with an automated response. Transparency is not merely a technical requirement; it is the cornerstone of public trust in a market that is fundamentally built on the promise of future security. By requiring companies to reveal their algorithmic processes, the Commissioner is ensuring that the transition to digital-first operations does not leave individual consumers in the dark regarding the factors that influence their financial stability.
Beyond the simple disclosure of methods, this initiative places a significant emphasis on identifying and eliminating the systemic biases that can inadvertently be woven into the fabric of artificial intelligence. If the training data used to build these models contains historical prejudices or if the underlying logic is flawed, the resulting algorithms can perpetuate unfair discrimination on a massive scale. This concern extends into the realm of personal privacy, as advanced analytical systems often require vast amounts of sensitive data to function effectively. Protecting this information from exploitation or mishandling is a primary objective of the state’s current regulatory framework, which seeks to align technological capabilities with the stringent protections of the Insurance Information and Privacy Protection Act. The goal is to create an environment where fairness is not sacrificed for the sake of speed, ensuring that every applicant is evaluated on their actual risk profile rather than through a distorted lens.
Ensuring Legal Accountability: Regulatory Requirements
A pivotal aspect of the new initiative is the clarification that legal responsibility remains entirely with the insurance carrier, regardless of who developed the technology being used. Many modern insurers rely heavily on third-party vendors and specialized InsurTech firms to provide the sophisticated software necessary for modern underwriting and fraud detection. However, Commissioner Ricardo Lara has made it explicitly clear that while a company can outsource its technological needs, it can never outsource its legal or ethical responsibilities to its policyholders. This policy ensures that insurers perform exhaustive due diligence before integrating any external tools into their workflows. It prevents a situation where a company might attempt to deflect blame for a discriminatory outcome onto a software provider. By maintaining this strict line of accountability, the state forces a higher level of internal scrutiny, pushing carriers to understand the inner workings of the products they purchase from the technology market.
To support this stance on accountability, the California Department of Insurance is signaling that periodic reviews will no longer be sufficient for companies utilizing high-stakes automation. Instead, there is an expectation for continuous monitoring and rigorous internal governance to ensure that algorithms do not drift over time or begin producing anomalous results. This requirement places a significant operational burden on insurers to maintain robust oversight committees that bridge the gap between technical data scientists and legal compliance officers. The state’s focus is on creating a culture of active stewardship where technology is viewed as a dynamic tool that requires constant human adjustment and verification. By reinforcing these standards, California is ensuring that the move toward automation does not result in a dereliction of duty toward the public. The legal framework is being shaped to reflect that every automated decision is ultimately a human choice made by the corporation, carrying the full weight of law.
Implementing Data Gathering and Risk Evaluation
Conducting the Responsible Use Survey: Market Analysis
Parallel to the public workshops, the department is conducting the Responsible Use of Artificial Intelligence Survey to capture the granular operational realities of the industry today. This survey is a mandatory requirement for a representative sample of the market, focusing on insurers and managing general agents that handle significant volumes of premiums in the state. By gathering empirical data on how AI is currently deployed in fields like underwriting and customer interactions, the department can build a comprehensive map of the technological landscape. The questions are designed to reveal the specific governance structures and internal oversight mechanisms that companies have already put in place to manage algorithmic risks. This data-driven approach allows regulators to identify industry best practices while also spotting areas where oversight might be lacking or inconsistent. It provides the necessary evidence to move from anecdotal concerns to targeted policy interventions.
The survey also delves into the extent to which the insurance industry relies on external technology vendors for their advanced analytical capabilities and decision-making tools. Understanding these interdependencies is crucial for assessing the systemic risks that could arise if a single software provider’s flawed algorithm is adopted by multiple carriers. The information collected will help the state evaluate the operational impacts and potential risks identified by the companies themselves, creating a shared understanding of the technological frontier. This initiative is not merely about data collection; it is about establishing a baseline of accountability that every market participant must meet. By analyzing the responses from a wide array of InsurTech firms and traditional carriers, the California Department of Insurance will be better equipped to draft regulations that are both effective and practical. This methodical gathering of information ensures that future rules are based on a realistic assessment of industry capabilities.
Balancing Innovation: Consumer Protections and Benefits
The initiative acknowledges that the integration of artificial intelligence offers several compelling benefits that can improve the overall efficiency of the insurance sector. Automated systems have the potential to significantly streamline the claims process, allowing for faster payouts and reducing the administrative burden on both the insurer and the policyholder. Furthermore, advanced algorithms can enhance fraud detection capabilities, identifying suspicious patterns that might be missed by manual reviews, which theoretically leads to more competitive pricing for the average consumer. These advancements are welcomed as part of a modern, efficient market that utilizes the best available technology to serve its participants. However, the state remains cautious about allowing these efficiencies to overshadow the primary goal of consumer protection. The challenge lies in fostering an environment where innovation is encouraged but does not come at the expense of accuracy or fairness.
Balanced against these operational advantages are the very real risks of inaccuracy and the potential for algorithms to amplify existing systemic biases without proper human review. The California Department of Insurance is particularly vocal about the dangers of a “hands-off” approach to technology, where automated systems are allowed to operate without sufficient oversight. Decisions made today regarding how these tools are governed will dictate the accessibility and fairness of the insurance market for decades to come. The state’s position is that any technological acceleration must be accompanied by a corresponding increase in regulatory vigilance to protect the public interest. This means ensuring that innovation is “responsible”—a term that implies a commitment to ethical standards and a refusal to sacrifice long-term equity for short-term corporate efficiency. By framing the discussion in this way, the Commissioner is signaling that the state will not tolerate progress that leaves vulnerable populations behind.
Establishing Long-Term Safeguards: Actionable Steps
The California Department of Insurance established a clear path forward by finalizing the preliminary phases of this statewide initiative, ensuring that the groundwork for responsible automation was firmly in place. Moving ahead, stakeholders should prioritize the development of internal auditing frameworks that align with the state’s emphasis on non-delegable responsibility and transparency. Insurers were encouraged to begin reviewing their third-party vendor contracts to ensure that data models were compliant with the evolving standards for fairness and bias mitigation. For consumer advocates and academic researchers, the focus shifted toward monitoring the implementation of these governance structures to ensure they effectively protected policyholders in real-world scenarios. The lessons learned from this comprehensive data-gathering phase provided the necessary insights to refine future regulatory proposals, ensuring that they were both practical and robust. Ultimately, the state’s proactive stance offered a blueprint for how to integrate advanced technology.
Building on these findings, the department moved to implement a series of review cycles that allowed for the continuous evaluation of algorithmic performance across different market segments. This approach ensured that the regulatory framework remained dynamic, adapting to new technological capabilities as they emerged in the fast-paced insurance landscape. Regulators focused on creating a standardized reporting format that allowed for easier comparison of AI governance across different firms, making it simpler to identify outliers and potential risks. These actions solidified the role of the human-in-the-loop requirement, making it a mandatory component for any high-stakes automated decision that affected policyholder coverage or costs. By emphasizing the need for ongoing education and collaboration between data scientists and legal experts, the initiative successfully bridged the gap between innovation and consumer rights. The final reports from this cycle emphasized that the integrity of the market depended on a permanent commitment to ethical AI deployment.