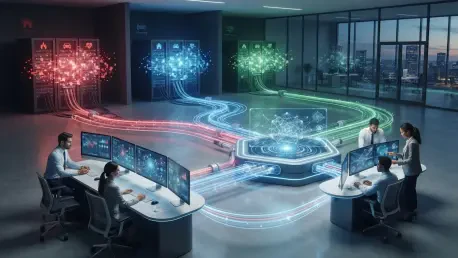
The disconnect between pricing, underwriting, and customer-facing teams often creates a bottleneck that slows down data-driven decision-making in volatile markets. In the current landscape of 2026, insurance carriers find themselves at a crossroads where massive datasets exist but remain trapped within departmental islands. This isolation prevents a holistic view of the customer, often leading to missed opportunities for personalized engagement or accurate risk assessment. While many firms have initiated pilot programs to test artificial intelligence, these efforts frequently stall due to the fragmented nature of legacy systems that were never intended to communicate with modern machine learning frameworks. The challenge is not merely technological but structural, as the traditional barriers between back-end actuarial science and front-end sales departments continue to persist. Consequently, the industry is witnessing a shift toward unified operational strategies that prioritize the flow of information across the entire lifecycle.
Bridging the Gap Between Legacy Infrastructure and Modern Intelligence
Building on this necessity for unification, the emergence of integrated platforms like the AIOS provides a blueprint for how companies can modernize without discarding their entire digital foundation. Rather than embarking on a multi-year overhaul of core legacy systems, insurers are increasingly adopting middle-layer solutions that sit atop existing infrastructure to link disparate models and applications. This approach allows for the synchronization of pricing engines with underwriting guidelines in real-time, ensuring that every quote generated is both competitive and risk-compliant. By creating a centralized environment where data from various business functions can converge, organizations can finally eliminate the manual hand-offs that traditionally delayed product launches or rate adjustments. This technical architecture facilitates a seamless transition from raw data ingestion to actionable intelligence, enabling a more responsive business model that can keep pace with shifting consumer behaviors observed from 2026 to 2028.
The realization of true operational agility depends on the ability to translate these technical connections into tangible customer experiences and streamlined workflows. When pricing and underwriting data are effectively linked with customer service operations, frontline staff gain the insights necessary to provide immediate and transparent explanations for premium adjustments. This level of clarity is vital in an era where policyholders demand more than just a bill; they seek a deeper understanding of the factors influencing their coverage costs. Furthermore, this connectivity ensures that every department operates from a single version of the truth, reducing the risk of conflicting information reaching the client. By empowering customer-facing teams with the same high-level intelligence used by actuaries, insurers can build stronger relationships based on trust and responsiveness. This strategy ultimately transforms the insurance lifecycle from a series of disconnected transactions into a cohesive journey that prioritizes the long-term customer retention.
Achieving Operational Excellence Through Unified Decisioning
As the scope of automated decision-making expands, the necessity for robust governance and explainability becomes the defining factor for long-term success in the financial sector. Because the insurance industry remains one of the most heavily regulated environments, the deployment of artificial intelligence must be accompanied by rigorous oversight and auditability. The models used to determine premiums or evaluate claims cannot function as black boxes; they must be fully transparent to satisfy both internal risk managers and external regulatory bodies. Solutions that provide a governed environment allow for full traceability, meaning every decision made by an algorithm can be deconstructed and explained in plain language. This transparency is not just a compliance checkbox but a strategic advantage that protects the organization from reputational risks and legal challenges. By embedding accountability into the heart of their AI strategy, insurers can confidently scale their automation efforts while maintaining the high standards of integrity.
In the final analysis, the transition toward a unified decision-making framework required a fundamental shift in how leadership perceived the intersection of human expertise and automated systems. Success was achieved when organizations recognized that while algorithms could handle the heavy lifting of data processing, the nuanced judgment of experienced underwriters remained indispensable for complex, high-stakes scenarios. The implementation of enterprise-wide coordination strategies allowed carriers to move beyond isolated experiments and achieve measurable business outcomes that improved overall performance. Moving forward, the industry learned that breaking down silos was a continuous process that demanded both cultural alignment and technical integration. Leaders who prioritized the synchronization of intelligence across departments found themselves better equipped to navigate the complexities of the modern market. This journey ultimately proved that the most resilient insurers were those who viewed data as a collective force that powered every facet of the enterprise.