The global insurance landscape is currently undergoing a radical metamorphosis as machine intelligence replaces actuary tables with real-time, predictive climate modeling systems. This transition marks the end of an era where disaster response was largely an exercise in financial recovery after damage occurred. Today, the focus has shifted toward a framework of proactive mitigation, where algorithms analyze the likelihood of atmospheric events before they manifest into catastrophic claims.
By integrating satellite imagery with historical vulnerability data, these systems provide a granular view of risk that was previously impossible to achieve. This shift is essential in the broader technological landscape, moving society from reactive chaos toward structured, data-driven risk management.
Evolution of AI in Climate Risk Management
Artificial intelligence has emerged as the foundational layer of modern risk management by synthesizing disparate environmental variables. Unlike traditional models that relied on historical averages, current AI systems leverage deep learning to anticipate how changing atmospheric conditions affect specific geographies. This evolution is driven by the necessity for more agile responses to increasing volatility in weather patterns.
The relevance of this technology lies in its ability to facilitate a shift from purely defensive insurance strategies toward active risk hardening. By identifying vulnerabilities before a storm or fire occurs, stakeholders can implement physical defenses that reduce the overall economic burden on the insurance pool.
Core Technological Components of Resilience Modeling
Predictive Risk Analytics and Data Synthesis
Modern models ingest massive datasets, including municipal records, historical claims, and hyper-local weather sensors. This synthesis allows insurers to identify specific risk concentrations, enabling a more precise allocation of hardening resources to the most vulnerable areas.
Such modeling is unique because it moves beyond static maps into dynamic simulations of urban environments. By accounting for local topography and infrastructure quality, these systems offer a level of detail that competitors using generic climate data cannot match.
Visual Language Models and Computer Vision
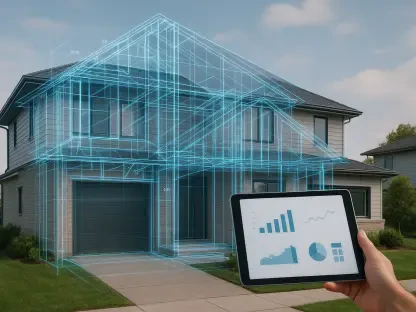
Computer vision and visual language models have revolutionized property assessments. Instead of manual inspections, AI-powered drones and satellites scan rooftops for structural weaknesses and monitor unmanaged vegetation for wildfire fuel.
This automation provides a continuous feedback loop for homeowners looking to protect their assets. The ability of AI to translate visual data into specific risk-hardening recommendations makes it a superior tool for maintaining long-term property value.
Modern Innovations and Strategic Shifts
Despite a wealth of data, a resilience gap has often persisted because information did not always translate into financial action. Innovations are now bridging this divide by transforming risk assessments into actionable metrics that attract large-scale institutional investors.
This strategic shift treats resilience as a distinct asset class where reduced disaster loss is viewed as a reliable return on investment. This helps convert abstract climate data into tangible funding for large-scale infrastructure projects.
Real-World Applications and Sector Deployment
Tangible results are already visible through initiatives like the “FORTIFIED” roof programs, which expanded across 34 states by leveraging AI to prove structural efficacy. These programs show that verified data can drive widespread adoption of safer building standards.
In regions prone to flooding, AI-modeled intelligence has successfully mobilized private capital for drainage reinforcements. When financial benefits are quantified through reliable intelligence, private markets commit capital without relying solely on limited government grants.
Technical and Regulatory Challenges
The path to adoption faces friction from data silos between private insurers and public agencies. Standardizing policy playbooks remains a significant hurdle, as various jurisdictions maintain different building codes and disclosure requirements.
Complexity in stakeholder-driven planning often slows capital deployment, requiring coordinated, interoperable data platforms. These platforms must ensure that technical insights are not lost in the administrative bureaucracy of local governments.
Future Outlook and Scalability
Looking ahead, AI is expected to catalyze district-backed resilience bonds and private-sector revolving loan funds. These financial instruments will allow cities to borrow against future savings generated by proactive disaster mitigation.
Potential breakthroughs in macro-trend synthesis could soon allow for the future-proofing of entire regions by predicting shifting climate patterns over the coming decades. This scalability ensures that both small communities and large metropolises can benefit from localized risk intelligence.
Final Assessment of AI-Driven Resilience
The integration of property intelligence and capital mobilization represented a fundamental shift in how the world addressed environmental volatility. This review found that AI-driven resilience was no longer a theoretical luxury but a necessary pillar of modern economic strategy. The technology successfully demonstrated that quantifying risk was the first step toward financing protection, thereby narrowing the gap between vulnerability and safety.
While regulatory hurdles persisted, the overall effectiveness of these systems in reducing the economic impact of climate change suggested that global adoption was inevitable. The transition to a data-first approach to resilience provided the clarity needed to secure a stable financial future for communities across the globe. This evolution paved the way for a more sustainable and predictable insurance market.