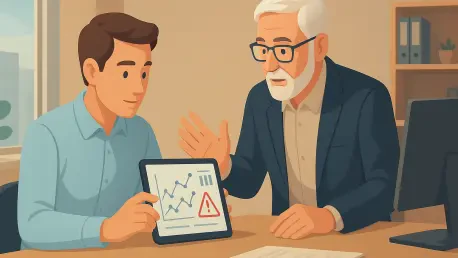
Underwriters are shifting their focus from the fear of job displacement to the urgent need for tools that provide historical context and decision support. While the rapid integration of artificial intelligence within the commercial property and casualty insurance sector promised a new era of efficiency, it has simultaneously introduced a complex tension regarding the preservation of professional judgment. Many organizations have prioritized high-volume data handling over the nuanced strategic thinking required for complex risk assessment. This trend suggests that while modern technology effectively manages the repetitive grunt work of the industry, it has yet to replicate the deep-seated intuition that defines expert underwriting. Consequently, the industry faces a significant challenge in 2026 as it attempts to balance the convenience of faster workflows with the necessity for high-caliber decision-making. Without addressing this imbalance, the sector risks eroding the very expertise that ensures long-term profitability and risk accuracy in an increasingly volatile market environment.
The Looming Threat of Institutional Brain Drain
A significant talent cliff is currently emerging as veteran professionals exit the workforce, taking decades of market intuition and specialized knowledge with them. This loss of institutional memory is now cited as a greater threat to the industry than the fear of being replaced by automated machines. In many firms, particularly within the United States, critical expertise resides solely in the minds of a few individuals who have spent years navigating specific market cycles. Despite this recognized risk, there remains a startling lack of formal systems designed to capture and codify this logic for future generations. Statistics indicate that while half of the current workforce values AI for reducing administrative burdens, only a small fraction believes these tools have actually improved the caliber of their decisions. This suggests a systemic focus on the mechanics of the process rather than the underlying logic, leaving younger underwriters to grapple with inconsistent data while under heavy pressure to perform.
Corporate spending remains heavily skewed toward end-to-end automation rather than robust knowledge transfer, even as the risk of losing senior judgment becomes more apparent. Only a tiny minority of firms prioritize investment in coaching or technology that documents the reasoning behind successful underwriting choices. This neglect creates a knowledge vacuum where the next generation of professionals may have access to sophisticated automation but lack the mentorship needed to handle unconventional risks. When expertise is siloed in a few veteran employees, the sudden departure of those individuals can leave a carrier unable to justify its risk appetite or maintain consistency in its book of business. Building a bridge between 2026 and 2028 requires a pivot toward systems that do not just process data, but also capture the logic behind every decision. Without these insights, the speed gained through automation becomes a liability, potentially leading to a series of uniform but fundamentally flawed risk assessments across the entire organization.
Strategic Next Steps for Sustainable Underwriting
To maintain a competitive edge, insurance carriers must realign their digital strategies to prioritize augmented intelligence over mere task completion. The future of the profession depends on tools that offer live portfolio signals and historical context, allowing humans to work smarter rather than just faster. This approach involves implementing systems that offer explainable outputs, detailing how similar risks performed in the past and how a new submission would influence the current book of business. When technology provides a reasoning framework, it helps bridge the gap for less experienced staff, acting as a digital mentor that reinforces best practices. However, this transition requires a conscious effort to move away from the black box nature of many early AI implementations. Instead of accepting an automated decision, the modern underwriter requires a partner that presents the evidence and supports a human-led conclusion. This synergy between man and machine is the only way to navigate the complexities of property and casualty risks in a global economy.
In the final analysis, successful firms recognized that the focus of digital transformation had to move beyond administrative efficiency toward the codification of senior expertise. Carriers that thrived began investing in technologies that actively documented the thought processes of their top performers, turning individual intuition into a collective institutional asset. They prioritized augmented intelligence that offered live portfolio signals, which allowed the workforce to navigate complex risks with greater precision. This strategic shift ensured that the time saved by automation was redirected into higher-level analysis, rather than being lost to the consequences of unguided decision-making. By the end of 2026, the industry understood that technology should serve as a bridge for knowledge transfer, helping to close the gap between veteran intuition and junior execution. These organizations eventually secured their market positions by fostering a culture where data-driven insights and human judgment operated in a symbiotic relationship.