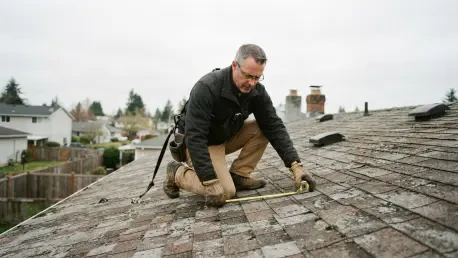
When a massive hailstorm tears through a quiet neighborhood, homeowners rely on their insurance policies as a final line of defense against financial ruin, yet many Oklahomans found themselves caught in a complex legal battle after State Farm allegedly mishandled their legitimate roof damage claims. This conflict recently culminated in a landmark $47.86 million settlement between State Farm and the Oklahoma Insurance Department following an exhaustive investigation into the carrier’s handling of residential roofing assessments. The state’s findings suggested that the company repeatedly violated the Unfair Claims Settlement Practices Act by denying claims that independent engineers later confirmed required full repair or complete replacement. This massive payout represents a significant turning point in the relationship between national insurance providers and state regulatory bodies, highlighting a growing demand for transparency in the assessment process as weather patterns become increasingly volatile in the region.
Financial Restitution: Allocating the Settlement Funds
The financial details of this agreement reveal a multifaceted approach to addressing the grievances of thousands of policyholders who were impacted by previous claim denials over the preceding years. A significant portion of the total settlement, approximately $35 million, has been established as a dedicated compensation pool for individuals whose roof claims were either underpaid or entirely rejected during the claims cycle starting in 2026. Beyond direct reimbursement, the deal allocated $10 million to fund the state’s FORTIFIED grant program, which incentivizes the installation of more resilient roofing materials capable of withstanding the extreme weather common to the Plains. This specific allocation aims to reduce future liability and protect homes against the increasing frequency of high-wind events. The remaining funds were earmarked to cover the extensive administrative and investigative costs incurred by the state during its thorough review of internal protocols and error rates.
While the monetary relief is substantial, the investigation also exposed a stark discrepancy between the company’s internal reporting and the actual reality faced by consumers. Although State Farm initially estimated its error rate at roughly 7 percent, the state’s independent audit uncovered a much higher 12.15 percent error rate, suggesting a systematic failure in how field adjusters evaluated structural damage. This gap in accuracy occurred during a timeframe when the company’s written premiums in the state grew by an impressive 93 percent, creating a perception that growth and profitability were prioritized over the consistent fulfillment of policyholder obligations. This disparity became a central pillar of the state’s argument, reinforcing the need for more rigorous oversight of the software and algorithms often used to automate claim decisions. The resolution of these discrepancies through a formal settlement avoids a protracted legal battle while forcing a re-evaluation of how damage thresholds are established for homeowners.
Regulatory Tensions: Scrutiny of the Opt-In Provision
A major point of friction in this resolution is the “opt-in” requirement, which mandates that homeowners must waive their right to pursue independent litigation in order to access their share of the settlement pool. This provision drew sharp criticism from high-ranking state officials, including Attorney General Gentner Drummond, who argued that such a clause essentially functions as a form of corporate protection rather than a genuine consumer remedy. Critics pointed out that by accepting these terms, State Farm avoided an official admission of wrongdoing while also securing a one-year moratorium on further investigations into these specific claim-handling practices through 2027. Furthermore, any funds from the $35 million pool that remain unclaimed by the end of the distribution period are slated to return to the company’s coffers. This structure has sparked a broader debate about whether mass settlements provide sufficient accountability or if they merely allow large corporations to budget for regulatory non-compliance.
To move forward effectively, policyholders should prioritize detailed property documentation and consider the benefits of the FORTIFIED program to enhance structural integrity before the next storm season arrives. The recent settlement demonstrated that regulatory pressure remains a vital tool for ensuring that insurance carriers adhere to the terms of their contracts and state law. In the past, the Oklahoma Insurance Department successfully leveraged these findings to secure a path for restitution, but the long-term efficacy of the deal depends on the willingness of consumers to participate in the claims pool despite the litigation waivers. Homeowners are encouraged to consult with independent structural engineers when initial claims are denied, as this data proved instrumental in the state’s ability to challenge the insurer’s findings. By transitioning toward resilient building standards and staying informed about regulatory developments, residents can better navigate the evolving and often contentious insurance landscape in 2026.