The presence of hazardous materials in aging infrastructure turns a simple property claim into a complex, time-consuming environmental remediation nightmare. The 2026 fire at the Tungatinah Power Station in Tasmania serves as a stark reminder that the insurance industry is struggling to keep pace with the complexities of modern industrial recovery. While most policyholders focus on the cost of replacing physical assets like turbines and buildings, the actual financial burden often lies in the overlooked expenses of site clearance and environmental remediation. Graham Peters of Crawford Australia notes that the price of simply preparing a site for reconstruction can now exceed the cost of the new build itself. This discrepancy highlights a systemic failure in how industrial risks are assessed, particularly concerning aging infrastructure and the “hidden” costs of disasters. As assets from the mid-20th century continue to dominate the industrial landscape, the gap between traditional coverage and modern reality continues to widen.
Industrial Risk: The Disconnect Between Policy and Costs
The Failure of Standard Valuation Formulas
A primary concern for heavy industry is the widening gap between ‘sums insured’ and the real-world expenses incurred during a total loss. Many corporations rely on traditional, formula-based approaches where debris removal and remediation are calculated as a fixed percentage of the asset’s value rather than a bespoke figure. This method is often a carryover from previous decades, updated only by standard inflation indexes rather than a rigorous evaluation of modern demolition and disposal costs. While a percentage-based sub-limit might work for a modern warehouse, it is woefully inadequate for massive, mid-century steel-and-concrete structures. The reliance on these outdated formulas creates a dangerous illusion of security, leaving companies exposed to millions in unfunded liabilities when the actual cost of clearing a site is tallied. Without a more granular approach to valuation, the industrial sector remains vulnerable to the soaring prices of specialized labor and debris management.
The Financial Burden of Legacy Infrastructure
The challenge of insuring facilities built in the mid-20th century involves addressing decades of historical and regulatory baggage. When these old assets are destroyed, the ‘quantum questions’ that arise are far more complex than a simple ‘like-for-like’ replacement. Owners often find that their insurance limits were set without considering the massive logistical undertaking required to dismantle compromised structural shells. Consequently, the indexed sub-limits provided by standard policies frequently fail to cover the actual costs of clearing the ground, leading to contentious and underfunded claims. These legacy sites often require sophisticated forensic engineering to ensure that demolition can proceed without endangering neighboring structures or the local environment. As the industrial base ages, the disconnect between the original design specifications and modern safety requirements becomes a central point of conflict during the claims process, often resulting in significant delays and financial shortfalls.
Regulatory Shifts: The Evolution of Environmental Standards
Impact of Hazardous Materials and Remediation
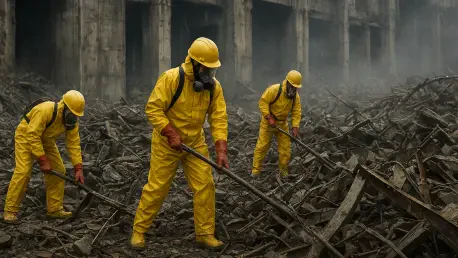
One of the most significant drivers of rising industrial insurance costs is the presence of hazardous materials, specifically asbestos, which was a construction staple decades ago. In the event of a disaster, what would have been a routine demolition project is transformed into a highly regulated environmental remediation effort. Modern health, safety, and environmental protocols require specialized labor and expensive disposal methods that were never factored into the original policy limits. These ‘hidden’ costs can balloon rapidly, leaving the policyholder to bridge a massive financial gap. The process of containing airborne particulates and managing toxic runoff requires specialized equipment and constant monitoring, all of which add layers of complexity and expense to the recovery timeline. When these factors are combined with the increasing scarcity of hazardous waste disposal sites, the financial impact on the insured party can be devastating, far exceeding the initial property damage estimates.
Navigating Modern Building Codes and Planning
Reinstating a legacy asset today requires more than just rebuilding; it necessitates compliance with current building codes, which often demand enhanced fire suppression, seismic protection, and energy efficiency. These mandatory upgrades mean that a ‘modern equivalent’ facility is inherently more expensive and complex than the original structure. Furthermore, legacy sites often face scrutiny from heritage and environmental agencies. These stakeholder requirements can delay construction for years, significantly inflating the ‘soft costs’ of a claim and extending the timeline far beyond what a standard policy anticipates. Navigating this web of bureaucracy requires dedicated legal and consulting teams, whose fees are often not fully covered by traditional insurance extensions. The result is a prolonged period of operational inactivity that can erode a company’s market share and financial stability. Modern industrial risk management must therefore prioritize regulatory agility as much as physical reconstruction.
Strategic Resilience: Operational Continuity and Loss Prevention
The Domino Effect of Asset Destruction
The destruction of a major industrial asset like a power station creates an immediate operational vacuum that extends far beyond physical property damage. For instance, when a facility responsible for a significant portion of a region’s energy supply goes offline, the owner must often secure expensive substitute generation to meet supply obligations. This ‘consequential loss’ can quickly surpass the value of the physical plant. In these scenarios, the ‘increased cost of working’ becomes a critical factor that many standard industrial policies fail to adequately address. The domino effect of a single asset failure can disrupt entire supply chains, leading to secondary losses that are difficult to quantify and even harder to recover. As the global economy becomes more interconnected, the importance of maintaining operational continuity through rapid mitigation becomes paramount. Insurance strategies must evolve to focus on the preservation of service delivery rather than just the replacement of hardware.
The Strategic Resilience of Indemnity Periods
The success of a business interruption claim depended heavily on the ‘indemnity period’—the length of time the insurer covered lost income and extra expenses. Because modern industrial assets took years to clear, redesign, and rebuild due to regulatory hurdles, companies realized that a short indemnity period left them exposed to massive costs long after the initial insurance payout was exhausted. Organizations began to transition toward bespoke indemnity calculations that accounted for the specific environmental and logistical challenges of their sites. They worked closely with adjusters to ensure that the wording of their policies explicitly included mitigation costs and the increased cost of working. By shifting the focus from simple property value to the duration of the outage, the industry moved toward a more resilient model of risk management. This proactive approach allowed firms to maintain their financial integrity during the long road to recovery, ensuring that the legacy of a disaster did not result in permanent closure.