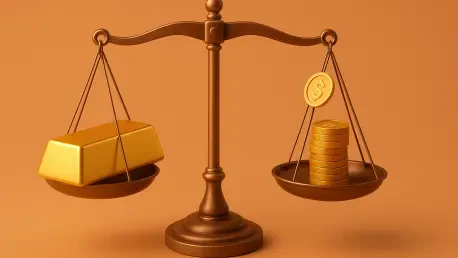
The seven point three percent payout rate of a single-premium immediate annuity for a sixty-five-year-old incorporates a return of principal that eventually leaves nothing for heirs. This reality creates a profound psychological and financial fork in the road for retirees who are standing at the threshold of their post-career lives with a substantial nest egg, such as seven hundred and ten thousand dollars. While the allure of a guaranteed, high-percentage monthly check is undeniable, the structural mechanics behind that payment often remain obscured by marketing jargon and a misunderstanding of how wealth is either preserved or consumed over a thirty-year horizon. Many individuals mistakenly compare these insurance products to traditional investment portfolios, assuming that a yield is a yield, regardless of its source. However, the fundamental difference lies in the ownership and eventual disposition of the underlying capital, which dictates not only the lifestyle of the retiree but also the potential financial legacy left behind for the next generation. Navigating this choice requires a deep dive into the mechanics of risk, inflation, and liquidity.
1. Structural Differences: Payout Rates and Annuity Payments
The most pervasive error in retirement planning occurs when an investor treats an annuity’s payout rate as an apples-to-apples equivalent to a stock portfolio’s dividend yield. In a single-premium immediate annuity, the insurance company calculates a payment based on the actuarial life expectancy of the buyer, effectively returning a portion of the original deposit in every monthly check. This means that while the headline percentage looks impressively high, a significant part of that money is simply the buyer’s own savings being handed back to them. By contrast, a dividend-focused portfolio aims to generate income solely from the earnings and profits of the underlying companies or assets, leaving the initial principal untouched and potentially growing over time. Understanding this distinction is vital because it changes the definition of income from a consumption of assets to a harvest of growth. Forgetting this detail can lead to a situation where a retiree believes they are earning a high return when they are actually depleting their own bank account.
A typical sixty-five-year-old today might see a quoted payout rate of approximately seven point three percent on a single-premium immediate annuity. While this figure appears robust, it is important to recognize that these payments are generally fixed for the duration of the contract, meaning they do not naturally adjust to the rising cost of living. Over a twenty-five or thirty-year retirement, the purchasing power of that fixed check can be severely eroded by inflation, making a comfortable lifestyle in the first year feel increasingly strained by the second decade. Furthermore, the decision to purchase such an annuity is almost always irreversible; once the free look period expires, the principal is gone, and the investor is locked into the payment schedule regardless of how their personal circumstances or the broader economic environment might change. The creditworthiness of the insurance provider also becomes a central concern, as the retiree is relying on the company’s ability to remain solvent for several decades, supported only by state guaranty associations.
2. Income Volatility: Market Fluctuations and Asset Reliability
In contrast to the steady nature of insurance contracts, a dividend portfolio is subject to the inherent volatility of the financial markets, which can lead to fluctuating monthly income. A common component of modern yield-seeking portfolios is the JPMorgan Equity Premium Income ETF, known as JEPI, which generates much of its distribution through the sale of covered call options. While this strategy can produce attractive yields, the income it provides is not fixed; it relies heavily on market volatility and the level of option premiums available in the current environment. When the markets are calm and volatility is low, the premiums shrink, leading to a natural reduction in the monthly distribution. For a retiree relying on this income to cover fixed expenses like housing or insurance, these swings can introduce a level of stress that an annuity completely avoids. The forward-looking distribution rate may sometimes trail the historical average, creating a situation where the expected paycheck is lower than what was advertised in past years.
To mitigate the risks of income volatility, many investors turn to seasoned corporate raisers that have a demonstrated history of increasing their dividends annually. Real estate investment trusts like VICI Properties and telecommunications giants like Verizon are often cited as pillars of stability in a retirement portfolio due to their consistent track records. VICI, for instance, has managed to raise its quarterly dividend every year since its inception, supported by long-term lease agreements with major gaming and hospitality operators. Similarly, Verizon has maintained a streak of over twenty consecutive years of dividend increases, with its leadership frequently describing the payout as a top priority for the firm’s capital allocation strategy. These types of holdings provide a vital counterweight to the more volatile elements of a portfolio, as they offer the potential for income growth that can help offset the effects of inflation. While they do not provide a lifetime guarantee like an annuity, the combination of reliable cash flow and growth makes them attractive to many owners.
3. Final Comparisons: Strategic Outcomes and Financial Guidance
Ultimately, the determination of which strategy is better depends entirely on an individual’s personal financial goals and their tolerance for various types of risk. The annuity typically wins the comparison for those whose primary objective is to maximize guaranteed monthly cash flow and who have no pressing need to leave a financial legacy to heirs. It provides a level of longevity insurance that a portfolio simply cannot match, as the insurance company is contractually obligated to keep paying even if the retiree lives for many decades. On the other hand, the dividend portfolio is the superior choice for individuals who prioritize flexibility, capital preservation, and the ability to adapt to changing economic conditions. While the portfolio requires more active management and carries the risk of market downturns, it keeps the original investment in the hands of the owner rather than the insurance carrier. This allows for potential growth in both the principal and the income, providing a hedge against the long-term erosion of purchasing power.
Navigating the decision between an annuity and a dividend portfolio necessitated a structured approach to finding the right financial consultant. The process began with the completion of a brief questionnaire that allowed for a match with vetted, fiduciary advisors specializing in retirement income. Individuals then reviewed their professional matches and selected a partner who aligned with their specific vision, ensuring their seven hundred and ten thousand dollars was managed with precision. This collaborative strategy provided a clear path toward balancing the need for immediate cash flow with the long-term goal of capital preservation. By analyzing historical distribution data and securing multiple annuity quotes, retirees moved forward with a plan that was both robust and adaptable. Ultimately, the successful transition into retirement was achieved by those who sought expert insights and remained diligent in their research. Taking these steps ensured that the chosen financial strategy supported a sustainable and fulfilling post-career life for years to come.