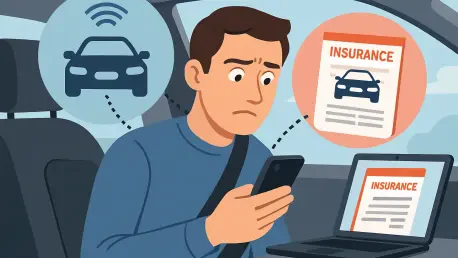
From 2016 until 2024, General Motors tracked driver behavior through its Smart Driver program, recording granular data points such as hard braking and rapid acceleration every three seconds. This silent surveillance transformed millions of modern vehicles into mobile data collection hubs, harvesting insights that drivers often believed were intended solely for personal safety feedback or maintenance alerts. Instead, this massive repository of driving habits became a lucrative asset for the corporation, feeding into a complex ecosystem of data brokers and risk assessment algorithms. The program operated under the guise of the OnStar service, subtly integrating behavioral monitoring into the daily commutes of unsuspecting owners. By capturing every sudden stop and high-speed maneuver with such high frequency, the automaker created a digital shadow of its customers. This practice raised profound questions about the boundaries of corporate oversight and the commodification of private movement in an increasingly connected automotive landscape.
Data Monetization and the Insurance Pipeline
The Hidden Engines: Behavioral Tracking and Telematics
The technical architecture behind the Smart Driver initiative relied on the deep integration of telematics units within the vehicle’s onboard diagnostic systems to monitor performance. These systems were capable of transmitting real-time performance metrics to central servers, where they were processed to create comprehensive driver profiles that were far more detailed than typical logs. Beyond simple speed monitoring, the sensors captured intricate details such as seatbelt usage, time of day for travel, and even precise geolocation coordinates for every trip. This level of granularity allowed the company to observe patterns that were previously invisible to external observers. While the interface marketed these features as a way for drivers to gain insights into their own efficiency, the underlying infrastructure was optimized for outbound data sharing. The sheer volume of information collected created a comprehensive record of a person’s life on the road, turning every errand and road trip into a data point for sale.
The Economic Impact: Higher Premiums and Broker Sales
Once this information was aggregated, it was transitioned into the hands of third-party data brokers who specialized in consumer risk reporting for the insurance industry. These brokers served as the bridge between the automotive manufacturer and insurance providers, packaging behavioral data into reports used to calculate individual premiums. For many consumers, the first sign of this data pipeline was an unexpected and unexplained increase in their insurance rates during their policy renewal. Insurers utilized the high-resolution logs of hard braking and acceleration to justify higher costs, treating every minor deviation from “perfect” driving as a significant liability indicator. This practice effectively bypassed traditional actuarial methods, which typically rely on historical accident records or traffic violations. By selling these insights, the manufacturer created a scenario where drivers were essentially paying twice: once for the vehicle and again through inflated insurance costs.
Accountability and the New Regulatory Landscape
Systemic Deception: Enrollment Tactics and App Failures
Investigations into the program revealed that the issues were not limited to the act of data collection itself, but extended to the deceptive methods used to enroll participants. In many instances, dealership employees were incentivized to sign customers up for the Smart Driver program during the vehicle delivery process to meet internal quotas. These employees frequently accepted the terms and conditions on behalf of the buyers, often without explaining what the program actually entailed or the privacy risks involved. Furthermore, technical discrepancies within the OnStar mobile application led to widespread misinformation; over 370,000 users were told they were not enrolled in the tracking program when, in fact, their data was actively being harvested. This systemic failure in obtaining informed consent formed the basis of legal actions across dozens of states. The resulting $220 million settlement reflected the gravity of these deceptive practices and the need for transparency.
Landmark Interventions: Settlements and Privacy Mandates
In response to these findings, the regulatory framework governing automotive data was significantly strengthened to prevent future abuses by large corporations. The Federal Trade Commission imposed a strict five-year ban on the sharing of geolocation and behavioral data with consumer reporting agencies, effectively cutting off the primary monetization route for this information. The company had to adhere to a rigorous data privacy program that mandated affirmative, explicit consent before any vehicle data could be collected or utilized in the future. This shift ensured that consumers regained the right to access, review, and delete their existing information, returning a degree of control to the vehicle owners. The settlement also required specialized training for dealership staff to ensure that future interactions regarding connected services were transparent. These actions established a new precedent for the industry, signaling that the era of unchecked surveillance in personal vehicles reached a critical turning point.