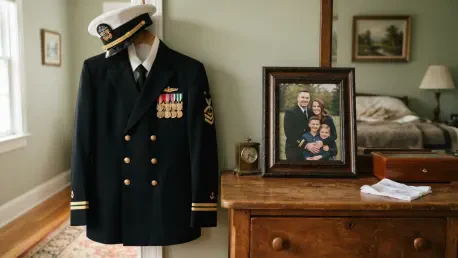
The decision to treat life insurance as a static administrative task rather than a dynamic financial strategy often leaves military families vulnerable during the most challenging transitions of their lives. While the Servicemembers’ Group Life Insurance provides a foundational level of protection that is both affordable and accessible, relying solely on these default settings throughout an entire career is a precarious financial strategy. As a service member moves from being a single trainee to a senior leader with a spouse, children, and a mortgage, the math of their financial protection must evolve accordingly. A failure to update these policies often stems from the high-tempo nature of military life, where administrative tasks are frequently pushed to the background in favor of operational readiness. However, an insurance policy is a living document that requires regular maintenance to remain effective. Without periodic oversight, the safety net that was sufficient at the start of a career may prove inadequate during a crisis.
Proactive Management: Career and Health Transitions
Securing Insurability: The Case for Early Private Coverage
One of the most significant advantages of reviewing insurance early in a military career is the ability to secure insurability before health complications arise. Many personnel mistakenly assume they can wait until they are closer to retirement or separation to seek private life insurance policies that supplement their government benefits. However, the physical and psychological toll of military service can lead to service-connected disabilities or chronic conditions that complicate private underwriting processes. By the time a service member reaches their final years of duty, they may find that private coverage is either prohibitively expensive or entirely unavailable due to their health history. Securing an individual policy while young and healthy allows a service member to lock in lower premiums and guarantees a level of protection that is not tied to their employment status.
This proactive step creates a permanent bridge of security that remains intact regardless of future health changes or career transitions. In 2026, the insurance market has become increasingly sophisticated, offering specialized products for the military community, yet the fundamental principle of “the younger, the better” remains the primary driver of affordability. Establishing a supplemental policy early ensures that even if a service member develops a condition that makes them uninsurable later, they already have a foundational layer of private protection. This is particularly important for those in high-risk occupational specialties where the likelihood of injury is elevated. By addressing this need now, personnel avoid the stress of trying to find coverage during the hectic period of military separation, when they should be focused on their next professional chapter.
Navigating Life Milestones: Adjusting Coverage for Growth
Life milestones serve as critical trigger points that demand a comprehensive evaluation of existing insurance limits and household financial goals. When a service member gets married, the financial landscape shifts immediately as a spouse becomes dependent on their income, necessitating a look at Family Servicemembers’ Group Life Insurance options. The birth or adoption of a child further increases this exposure, as long-term obligations like childcare and future college tuition must be factored into the coverage amount. Furthermore, a Permanent Change of Station often involves significant shifts in housing costs and the potential loss of a second income if a spouse must leave their job. Each of these events changes the amount of capital required to keep a family solvent in the event of a tragedy. Reviewing insurance during these transitions ensures that the policy remains a reflection of current reality.
As debt levels grow with the purchase of a home or the acquisition of personal loans, the initial SGLI cap of $500,000 may no longer be sufficient to pay off all liabilities and provide a lasting income stream for survivors. It is a common mistake to view insurance only as a means to cover burial costs rather than a tool for wealth preservation and debt elimination. A thorough review involves calculating the total “financial gap”—the difference between a family’s existing assets and their long-term needs. This calculation must be adjusted whenever a significant lifestyle change occurs, such as a promotion or a move to a high-cost-of-living area. By aligning coverage with current expenses, service members can rest assured that their families will not be forced to make drastic lifestyle sacrifices during an already difficult period of mourning.
Ensuring Administrative Accuracy and Civilian Transitions
Administrative Diligence: Synchronizing Beneficiary Designations
Administrative diligence is just as important as the total dollar amount of a policy, as outdated beneficiary information can lead to severe legal and financial complications. A common pitfall for service members is the assumption that updating one military form automatically updates all others across the various personnel systems. For instance, the SGLI beneficiary designation and the Record of Emergency Data, also known as DD Form 93, are distinct documents that serve different purposes and are maintained in different databases. Failing to synchronize these forms after a divorce or remarriage can result in life insurance proceeds being paid to an ex-spouse or a former household, contrary to the member’s current wishes. Utilizing the SGLI Online Enrollment System through the milConnect portal allows for real-time updates and ensures all designations are legally binding.
The complexity of beneficiary designations extends to how funds are managed for minor children, which is another area where regular reviews are essential. Without a clear trust or guardianship arrangement, insurance payouts intended for children may be delayed by court proceedings or managed by unintended parties. During a review, service members should verify that their primary and contingent beneficiaries are listed correctly with up-to-date contact information. This process eliminates “stale” data that causes friction and delays during the claims process. In the high-stress environment of a deployment, having the peace of mind that administrative paperwork is flawless allows the individual to focus entirely on the mission. Ensuring that the legal and administrative components of an insurance plan are current is the only way to guarantee that the intended recipients receive support without delay.
Strategic Financial Alignment: Achieving Long-Term Security
The most effective approach to military life insurance involved a proactive stance that treated financial protection as a core component of overall mission readiness. Service members who prioritized these reviews ensured that their beneficiary designations remained accurate and that their coverage amounts reflected the true cost of their families’ long-term needs. By utilizing the SGLI Online Enrollment System and seeking supplemental private policies early, personnel successfully bridged the gap between active-duty benefits and the realities of the civilian market. These actions transformed life insurance from a neglected line item on a pay stub into a robust shield against uncertainty. The shift in perspective allowed families to navigate the complexities of permanent changes of station and eventual retirement with greater confidence.
Future success in financial planning required a holistic view that combined government benefits with private assets and clear administrative records. Service members who took the time to educate themselves on the 120-day SGLI conversion window avoided the pitfalls of sudden coverage lapses during their transition to veteran status. They also recognized that financial security was never a finished product but an ongoing commitment to their families’ future. By conducting annual check-ups or reviews during major life events, personnel maintained a level of protection that was as dynamic as their careers. Ultimately, the diligence applied to these administrative details provided a legacy of security that outlasted the duration of their uniformed service. Moving forward, the integration of digital management tools and professional financial advice will continue to be the best defense against unforeseen risks.