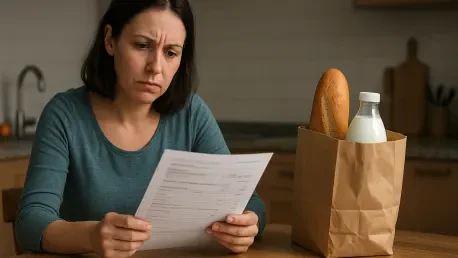
Low-income households are increasingly switching to lower-quality food providers to offset the rising cost of their private health insurance premiums. This shift reflects a broader, systemic crisis as American families grapple with a landscape of intense financial volatility. Recent data indicates that health insurance premiums are projected to see double-digit increases across the board for the upcoming cycle. Specifically, the Affordable Care Act Marketplace is bracing for a median premium hike of 15% for the upcoming cycle. This comes on the heels of a previous cycle that saw a 20% finalized increase, creating a compounding effect that stretches domestic budgets to their limits. While the individual market only represents a small fraction of the total population, it acts as a critical bellwether for the broader private insurance sector. Rising pharmaceutical and hospital costs are pushing prices to record highs, making the prospect of maintaining coverage a daunting challenge for many middle-class citizens who no longer qualify for federal aid. The average annual cost for family coverage has now reached $27,000, creating an unsustainable burden for the workforce.
The Economic Drivers: Historical and Policy Factors
The current affordability crisis is the result of decades of escalating costs that have consistently outpaced general economic growth and wage increases. In the early 1970s, healthcare spending accounted for roughly 7% of the United States Gross Domestic Product; however, by 2026, that figure has soared to 17%. A major catalyst for the recent “sticker shock” in premiums was the expiration of enhanced federal subsidies that previously shielded many consumers from the full weight of rate hikes. Without these financial buffers, individuals are now feeling the direct impact of a 10.8% increase in the underlying cost of providing medical services. The removal of this support has left many families in a precarious position, as they are now forced to pay the full market price for plans that were once made affordable through government intervention. This shift highlights the inherent instability of relying on temporary policy measures to address the systemic issue of healthcare inflation, which continues to grow despite various legislative attempts to curb its expansion.
Escalating Inflation and the Expiration of Federal Subsidies
The inflationary pressure within the medical sector is further exacerbated by the rising costs of pharmaceutical products and specialized hospital services. As the underlying expenses for providers increase, these costs are inevitably passed down to the consumer in the form of higher monthly premiums and expanded deductibles. For the average American family, these statistical shifts translate into a daunting financial hurdle that often exceeds their annual savings. Annual premiums for family coverage have climbed to heights that were unimaginable just a decade ago, often paired with individual deductibles nearing $2,000. This mounting pressure is making it increasingly difficult for households to maintain their standard of living, as health insurance costs outpace wage growth and consume a larger share of the domestic budget. The expiration of pandemic-era financial protections has only served to accelerate this trend, leaving the most vulnerable populations exposed to market forces. Without a significant shift in how medical services are priced at the point of care, the upward trajectory of insurance costs is expected to persist.
Disparities Between Private Insurer and Medicare Pricing Models
A significant disparity exists between what private insurers pay for services compared to government-negotiated rates, pointing to deep inefficiencies in the commercial market. Between 2026 and 2028, this gap is expected to widen as private insurance prices for hospital care continue to surge, significantly outpacing the rates seen in Medicare. Historically, private insurance prices for hospital care surged by 30%, which was significantly higher than the 21% increase seen in Medicare rates during the same period. This discrepancy suggests that private sector pricing models are primary drivers of the inflation seen in household premiums, as insurers pass these higher service costs directly to their policyholders. In many cases, the commercial market effectively subsidizes the broader healthcare infrastructure through these inflated rates, which families are finding increasingly difficult to sustain. This dynamic creates a feedback loop where hospital systems demand higher payments from private entities to compensate for lower public reimbursements, further tightening the financial noose on the American consumer.
The Human and Financial Cost: Hardship and Resilience
The socioeconomic consequences of these rising costs are forcing many Americans, especially those on fixed incomes, to make difficult trade-offs that impact their quality of life. To keep up with premiums and medication costs, some citizens are cutting back on essential utilities like internet and cellular service or are dramatically altering their nutritional habits by switching to cheaper, processed food options. The impact is especially visible among the elderly, with a notable rise in “unretirement”—a phenomenon where retirees return to the workforce out of pure financial necessity. Nearly half of those re-entering the labor market cite medical expenses and insurance premiums as their primary motivation for leaving retirement. Additionally, there has been a significant increase in communal living arrangements as seniors seek roommates to split the high costs of daily living and healthcare. This loss of independence and the sacrifice of basic comforts are direct results of a system where the cost of staying healthy now consumes a disproportionate share of the budget.
Socioeconomic Consequences for Retirees and Low-Income Families
While households are downsizing their lives to afford basic care, the entities managing their health risks are expanding their market caps and reporting robust shareholder dividends. The financial strain is not distributed equally across the economy, as evidenced by the record-breaking revenues reported by major insurance conglomerates. For instance, companies like CVS Health and Elevance Health have seen multi-billion-dollar revenues and substantial operating gains, often driven by higher premium yields. Even as consumers pay more for their health coverage, the medical benefit ratio—which tracks the percentage of premiums actually spent on patient care—has shown a decline in several major sectors. This suggests that a smaller portion of premium revenue is being directed toward direct patient services, even while corporate profits continue to rise. This growing disconnect between the profitability of the insurance industry and the affordability of care for the general public raises serious questions about equity. The data suggests that without policy intervention, the burden on the American consumer will continue to intensify.
Sustainable Strategies for Navigating the Healthcare Crisis
The healthcare crisis reached a critical juncture where policymakers were forced to consider radical shifts in how medical services were financed and delivered. Instead of relying on short-term subsidies, the focus shifted toward aggressive price transparency and the regulation of pharmaceutical costs to address the root causes of medical inflation. Households that successfully navigated this period often did so by utilizing high-deductible plans paired with health savings accounts, though this was only a temporary fix for a systemic problem. Looking ahead, the industry moved toward value-based care models that prioritized patient outcomes over the volume of services rendered, which helped to stabilize some of the more volatile pricing structures. For families, the most effective strategy involved proactive engagement with patient advocates to negotiate hospital bills and seeking out community-based resources for medication assistance. These steps, combined with a stronger emphasis on preventative care, offered a path forward that sought to decouple the quality of one’s health from the volatility of their monthly insurance premium.