While the finance and insurance sector contributes 3.37% to Nigeria’s national real GDP, the insurance subsector currently accounts for a mere 12.78% of that output. This disparity highlights a stark paradox within the economy: while insurers have successfully raised approximately ₦700 billion to stabilize their operations, the public’s appetite for their products remains remarkably low. Current data suggests that the industry contributes less than 1% to the total GDP, leaving a vast majority of the population and their assets completely unprotected. This financial milestone marks the end of a long period of regulatory uncertainty and serves as the starting point for a strategic shift toward deeper market penetration. The focus has now moved from surviving regulatory scrutiny to creating a sustainable and inclusive market for all. The landscape of the Nigerian financial services industry is currently undergoing a profound metamorphosis, characterized by a massive influx of capital that promises to redefine the boundaries of domestic risk management.
Strengthening Financial Resilience and Local Capacity
Enhancing Risk Retention: A New Era of Local Underwriting
The massive ₦700 billion recapitalization exercise has effectively recalibrated the domestic insurance landscape by providing companies with the financial muscle required to retain high-value risks locally. Historically, many Nigerian insurers were forced to cede a significant portion of their premiums to international reinsurers because they lacked the balance sheet strength to handle massive claims from sectors like oil, gas, and major civil infrastructure. This trend often led to substantial capital flight and limited the growth of the domestic industry. By bolstering their capital bases, local firms can now participate more aggressively in these lucrative sectors, ensuring that the financial rewards of national development remain within the Nigerian economy. This shift is not just about meeting regulatory thresholds but about positioning the industry as a central pillar of national economic stability. As firms begin to underwrite larger and more complex projects, the effect is expected to foster a more resilient financial environment for all.
Internal Modernization: Beyond Regulatory Compliance
Beyond the immediate goal of risk retention, the capital injection serves as a vital resource for the internal modernization of insurance providers across the country. Leading companies are now utilizing these funds to upgrade their technological infrastructure and professionalize their workforces to meet global standards. The transition involves moving away from traditional, manual processes toward automated systems that improve accuracy and efficiency. This evolution is necessary because capital alone cannot stimulate market demand; it must be coupled with a fundamental change in how insurance is perceived by the average citizen. Industry experts argue that for the sector to grow, it must shift the narrative from insurance being a compulsory regulatory burden to it being an essential financial safety net for households and small businesses. By investing in better human capital and sophisticated operational frameworks, insurers are building the foundation required to deliver more sophisticated products that cater to a modernizing economy.
Overcoming the Trust Deficit Through Technology
Building Public Confidence: A Customer-First Approach
The most formidable barrier to expansion remains a deep-seated distrust among the Nigerian populace, often fueled by historical delays in claims settlements and opaque policy terms. To counter this, the sector is undergoing a strategic shift toward a customer-first philosophy that prioritizes transparency and ease of access above all else. By leveraging diverse distribution channels such as bancassurance and authorized local agents, insurers are attempting to reach underserved populations who have traditionally been excluded from the financial ecosystem. This approach aims to humanize the industry and make insurance products more relatable to the daily needs of individuals and entrepreneurs. Bridging the confidence gap requires more than just marketing; it necessitates a tangible improvement in the quality of service and a commitment to honoring obligations promptly. As companies expand their footprint through these new channels, the goal is to integrate insurance into the broader financial habits of Nigerians, fostering a culture of risk mitigation.
Digital Solutions: Revolutionizing Claims Processing
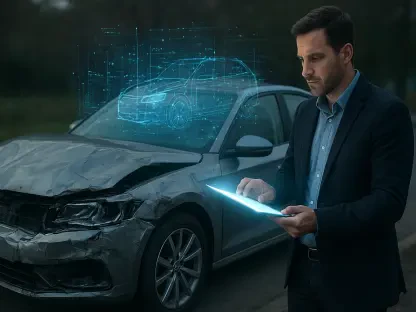
Digital transformation has emerged as the primary tool for resolving the trust crisis, particularly in the critical area of claims processing which has long been a pain point for consumers. By adopting advanced platforms like Curacel, which facilitate mobile vehicle inspections and real-time data integration, companies are drastically reducing the time it takes to settle claims. These digital tools allow customers to submit photo evidence and receive repair estimates almost instantly, eliminating much of the bureaucracy that previously defined the industry. This move toward a technology-driven model not only improves operational efficiency but also provides the level of transparency required to convince skeptical consumers that their policies will be honored. Furthermore, the use of data analytics enables insurers to price their products more accurately and offer personalized coverage that reflects the actual risk profile of the user. By making the entire lifecycle of an insurance policy visible, the industry is finally addressing the root causes of skepticism.
Strategic Synergies and the Path to Market Expansion
Market Integration: The Intersection of Insurance and Property
A robust insurance sector is essential for the long-term stability of Nigeria’s real estate and housing markets, especially as property values and construction costs continue to rise. Insurers provide the necessary protection against fire, flooding, and structural failure, which in turn gives lenders the confidence to extend credit for mortgages. This synergy between insurance and property finance is a critical component of a healthy economy, ensuring that long-term investments are shielded from unforeseen disasters. As the government and private developers push for increased housing stock, the role of insurance as a risk-mitigation tool becomes even more prominent. Without adequate coverage, a single catastrophic event could wipe out years of investment and stall development projects indefinitely. Therefore, the expansion of the insurance market is directly linked to the success of the broader real estate ecosystem. By securing assets, insurers are helping to create a more predictable environment for property investment and urban growth.
Future Growth: Consolidation and Core Underwriting
The future of the industry will likely be defined by a period of intense consolidation, where firms specialize in their strongest niches or merge to create more competitive entities. Recent financial performances show that while investment income has bolstered profits during the recapitalization phase, the next challenge is to drive growth through core underwriting activities. Success in the coming years will be measured not just by the size of balance sheets, but by how effectively the industry increases its contribution to the national GDP. We are already seeing insurers move beyond the capital hunt to a market hunt, focusing on product innovation and the speed of service delivery. This transition requires a departure from the reliance on fair-value gains and a return to the fundamental principles of insurance: assessing risk and providing protection. As firms streamline their operations and target specific demographics, the overall efficiency of the sector is expected to improve, moving the industry toward the center of the financial system.
Delivering Excellence in a Competitive Financial Landscape
The conclusion of the recapitalization phase represented a critical victory for the Nigerian insurance sector, yet the real work began the moment the financial targets were achieved. Industry leaders recognized that the surplus capital served only as a tool, and that its ultimate value depended on how effectively it was deployed to serve the consumer. By prioritizing digital innovation and focusing on local risk retention, firms successfully laid the groundwork for a more transparent and resilient industry. Moving forward, the most impactful next step for insurers should be the aggressive expansion of micro-insurance and agricultural products to capture the millions of Nigerians currently outside the formal financial net. Additionally, forming deeper partnerships with the telecommunications sector could provide the necessary infrastructure for mass-market distribution. These strategic shifts established a clear path toward doubling the sector’s GDP contribution and demonstrated that growth was paved with service quality rather than just compliance.