The role of geography in claim outcomes is becoming increasingly significant, with regions like Florida and Texas identified as high-pressure jurisdictions for legal representation. This phenomenon highlights a broader challenge for the middle market, a sector defined by organizations generating up to one billion dollars in annual revenue. These firms often occupy a unique and sometimes precarious economic space; they have moved past the simplicity of small business models but have not yet constructed the massive internal risk management infrastructure characteristic of global conglomerates. Without a dedicated in-house risk manager to navigate these complexities, many middle-market companies find themselves at a strategic disadvantage. They must rely heavily on external brokers and carriers to identify and mitigate risks that could jeopardize their stability. This dependency underscores the urgent need for more integrated, sophisticated insurance solutions that bridge the gap between resource-rich giants and smaller, more agile enterprises in the 2026 landscape.
Identifying Hidden Vulnerabilities
Unrecognized Exposures: The Professional Liability Gap
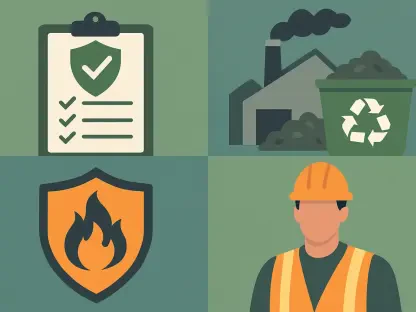
Many middle-market firms operate under a dangerous misconception regarding the scope of their primary insurance policies. For instance, a manufacturing or technology company may believe that a standard general liability policy provides a blanket safety net for all operational errors. However, these organizations frequently discover that professional mistakes—errors and omissions—are excluded from such coverage, a realization that often only surfaces after a claim has been officially denied. This “invisible” risk gap represents a significant threat to financial health, as the costs of litigation and settlement for professional errors can easily exceed the liquidity of a mid-sized firm. To combat this, carriers are now moving toward integrated product suites that proactively include Errors and Omissions (E&O) and pollution liability components. By combining these essential protections, insurers ensure that standard industrial processes, which might involve hazardous materials or specific waste disposal protocols, do not become the catalyst for an unrecoverable financial disaster for the unwary client.
Evolving Loss Patterns: Retail and Fleet Dynamics
Beyond specific coverage gaps, the very nature of loss trends is undergoing a fundamental transformation across diverse sectors. In the retail and hospitality industries, there has been a noticeable uptick in the frequency of general liability claims, largely driven by high foot traffic and shifting consumer behaviors in a post-digital world. Simultaneously, businesses that maintain distribution fleets are facing a different but equally pressing challenge: an increase in the severity of automobile-related losses. These are not just simple accidents but complex legal events where the financial stakes have risen significantly due to inflation and social litigation trends. Consequently, middle-market companies can no longer afford to maintain static, “set-and-forget” insurance programs. Instead, they must work with partners who utilize real-time data to adjust safety protocols and fleet management strategies. This dynamic approach allows firms to address the physical and operational risks of 2026 before they manifest as massive liabilities on the corporate balance sheet.
Strategic Operational and Legal Responses
Jurisdictional Pressures: Managing Legal Exposure
Geography has become a primary driver of insurance costs, as the legal environment varies drastically from one state to another. In high-pressure regions like Florida and Texas, the involvement of attorneys in claim files is significantly higher than the national average, which inevitably leads to more aggressive litigation and higher settlement demands. For a middle-market firm, which typically lacks the robust internal legal department of a large corporation, navigating these waters is exceptionally difficult. The increased severity of claims in these jurisdictions forces companies to reconsider their entire approach to risk defense and valuation. Carriers that possess deep local expertise are becoming indispensable, as they can provide the necessary guidance to manage claims within these specific legal frameworks. This regional focus is no longer an optional luxury but a core requirement for any business operating across state lines, where a single incident in a litigious area can impact the total cost of insurance for the entire organization during the fiscal year.
Financial Strategy: The Shift to Loss Sensitivity
As middle-market entities approach the higher end of the revenue spectrum, their financial capacity to absorb certain levels of risk begins to evolve. This maturity has led to a significant trend where firms move away from traditional “guaranteed cost” programs toward loss-sensitive structures. By opting for programs that include large deductibles—often ranging from $100,000 to $250,000—companies can take a more proactive role in their risk outcomes. This shift is not merely a cost-saving measure but a strategic financial decision that allows a business to benefit directly from its own successful safety and risk mitigation efforts. When a company has “skin in the game” through a loss-sensitive program, the motivation to improve internal protocols and reduce incident frequency becomes a direct driver of profitability. This evolution reflects a broader transformation where insurance is viewed as a sophisticated tool for capital management rather than a simple overhead expense, providing a path for firms to stabilize their long-term insurance expenditures.
Risk Engineering: Bridging the Resource Divide
In the absence of an internal risk manager, the role of the carrier’s risk engineering team has become the ultimate differentiator in the middle-market segment. These engineers act as “trusted advisors,” providing expertise that many mid-sized firms could not afford to hire independently. This partnership goes far beyond the traditional underwriting process; it involves hands-on operational support tailored to the specific needs of each client. Whether a company is opening a new manufacturing facility or updating its production technology, risk engineers provide the critical oversight needed to identify potential hazards before operations begin. They assist in developing customized safety plans and refining internal protocols to match the highest industry standards. By implementing these best practices, middle-market firms can improve their overall risk profile. This proactive stance makes them more attractive to the global insurance market and fosters a culture of safety that permeates every level of the organization, ensuring long-term resilience and operational continuity.
Technological and Geographic Expansion
Digital Transformation: Efficiency and Market Access
The landscape of middle-market insurance is being rapidly reshaped by a dual expansion of physical presence and digital capabilities. Geographically, major carriers are striving for comprehensive domestic coverage while simultaneously establishing strong footholds in international hubs such as Vancouver and Toronto. These expansions are critical for middle-market firms that are increasingly looking to operate across borders, necessitating cross-border programs that handle varied regulatory requirements seamlessly. On the technological front, the industry has embraced advanced rating and quoting platforms that have revolutionized the submission process. By streamlining these workflows, insurers can provide faster feedback to brokers and their clients. Even more transformative is the integration of Artificial Intelligence into the underwriting process. AI algorithms are now capable of digesting vast amounts of data within a submission almost instantly, allowing underwriters to identify patterns and assess risks with a level of precision and speed that was previously impossible, thereby improving the overall accuracy of policy pricing.
Strategic Roadmap: The Rise of Industry Verticals
Looking toward the horizon of 2027 and beyond, the trajectory for the middle-market insurance sector is defined by increasing specialization and the development of dedicated industry verticals. The industry has moved away from a one-size-fits-all approach, instead creating highly specialized units for construction, technology, healthcare, and private equity. These verticals allow for the creation of insurance products that are finely tuned to the specific legal and operational challenges of each sector. The successful carriers of this era are those that position themselves as strategic partners rather than mere commodity providers. By offering a high-touch, consultative model, these partners provide the necessary expertise, technology, and risk engineering support to bridge the internal resource gaps of growing businesses. Middle-market firms are best served by adopting a holistic view of risk, integrating loss-sensitive financial structures with advanced safety protocols. This comprehensive strategy ensures that companies are prepared for the emerging complexities of a globalized economy, ultimately securing their future through informed decision-making and robust external partnerships.