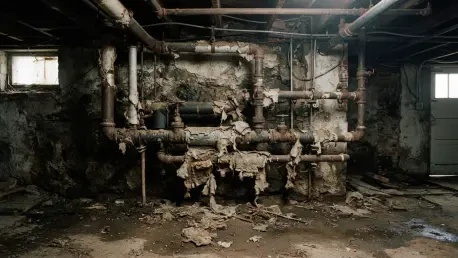
The recent discovery of more than 1,650 hazardous material deposits within one of the world's most heavily monitored government buildings has completely dismantled the popular assumption that asbestos was successfully banished to the history books decades ago. This startling revelation regarding
The principle of fortuity prevents businesses from obtaining new insurance coverage once a potential energy disruption has already been publicly announced or anticipated. In the current global landscape of 2026, the rise of energy nationalism has transformed how multinational corporations perceive
The rise of clinical decision support systems and AI triage platforms necessitates a blended insurance architecture that addresses both algorithmic accuracy and human clinical judgment. As patient care increasingly moves away from physical examination rooms toward data-driven, virtual environments,
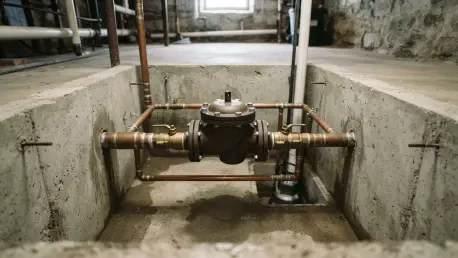
Sewer backup coverage remains an optional addition to standard policies, leaving many unprotected unless they specifically secure this endorsement before water damage occurs. This critical gap in coverage highlights a broader issue of climate literacy that homeowners must address as atmospheric
Modern insurance distribution requires a seamless transition between automated data gathering and the nuanced judgment provided by experienced human advisors in high-risk coastal markets. Currently, the American homeowners' insurance landscape is navigating a profound period of disruption, where
Small business owners in the United Kingdom are currently operating within a precarious landscape where a significant portion of their assets remains vulnerable to unforeseen financial shocks. Recent industry research involving over one thousand entrepreneurs has revealed a startling protection gap
1 2 3 4 5 6 7 8 9 10 11 12 13 14 15 16 17 18 19 20 21 22 23 24 25 26 27 28 29 30 31 32 33 34 35 36 37 38 39 40 41 42 43 44 45 46 47 48 49 50 51 52 53 54 55 56 57 58 59 60 61 62 63 64 65 66 67 68 69 70 71 72