The escalating price of corrective work is tethered to global supply chain disruptions, making professional liability claims more expensive to resolve than ever before. While architectural and engineering firms have historically focused on the frequency of claims as a primary metric for risk, the contemporary landscape has shifted focus toward the sheer volatility of claim severity. In the current market, even as the number of claims remains relatively stable or experiences a slight downturn in specific sectors, the financial weight of each individual settlement has ballooned to historic proportions. Recent industry data reveals that the average severity of professional liability claims in North America has increased by approximately 62% in nominal terms over the last decade. This surge is not merely a reflection of a few outlier cases but represents a systemic upward shift across multiple disciplines. When adjusted for inflation, engineering firms have faced a real-dollar severity increase of 22%, while architectural practices have seen a 13% jump. This divergence between how often mistakes happen and how much those mistakes cost to rectify has forced a fundamental reevaluation of risk management within the professional services sector.
The Financial Burden of Defense and Fault Allocation
A significant driver behind the skyrocketing severity of claims is the increasing cost associated with defending a firm’s work, regardless of the ultimate merit of the accusations. So-called “expense-only” claims, which are cases that conclude without any indemnity payment being made to the claimant, have become a massive financial drain on the industry. Between 2016 and 2025, these claims represented nearly a third of the total claim volume in the North American professional liability portfolio, yet they generated hundreds of millions of dollars in defense and allocated loss adjustment expenses. The mechanics of modern litigation mean that even a successful defense is an expensive endeavor. This is partly due to more aggressive prosecution strategies employed by plaintiffs and the necessity of navigating high-priced expert witness testimony. As design and construction projects grow more technically complex, the digital trail of eDiscovery requires significant resources to manage, extending the duration of the legal process and allowing legal fees to accrue at an alarming rate over several years of litigation.
Furthermore, the legal principles governing how fault is allocated among various project participants often result in professional firms paying settlements that are vastly disproportionate to their actual degree of negligence. In many jurisdictions, the doctrine of joint and several liability permits a claimant to recover the full amount of damages from any party involved in a project, regardless of that party’s specific percentage of fault. This creates a scenario where an engineering or architectural firm might be found only 10% responsible for a failure, yet they are forced to pay the entire settlement if other contractors or stakeholders are underinsured or insolvent. Industry records show that tens of millions of dollars have been paid out on claims where the insured’s liability was determined to be less than 50%. This inherent imbalance in the legal system acts as a multiplier for claim severity, as firms with “deep pockets” or comprehensive insurance coverage are targeted for larger payouts, regardless of the technical nuances of the professional error in question.
Macroeconomic Drivers and the Impact of Project Scale
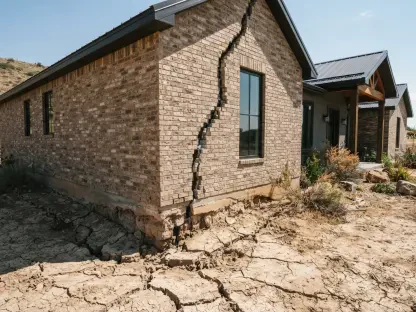
The external economic environment is perhaps the most visible catalyst for the rising costs of professional liability. Construction material prices, labor costs, and the expense of demolition and debris removal have all seen sharp increases, rising by more than 45% in recent years. Because professional liability claims often involve some form of “corrective work”—fixing a structural defect, replacing an incompatible material, or redesigning a faulty system—the cost of the remedy is directly tied to the current market rates for construction. A design error that might have cost $500,000 to fix several years ago now carries a price tag nearing $750,000 simply due to the higher cost of the steel, concrete, and skilled labor required to perform the remediation. This inflationary pressure creates a higher “floor” for all claim negotiations, as the baseline cost of physical repairs provides a starting point for settlements that is significantly higher than what was seen in previous economic cycles.
Parallel to these inflationary trends is the increasing physical and financial scale of modern infrastructure and commercial developments. The prevalence of “mega-projects”—those with a total value exceeding $1 billion—has nearly doubled as a portion of overall construction spending within the United States over the last five years. On projects of this magnitude, the margin for error is razor-thin, and the consequences of even a minor professional oversight are magnified exponentially. A small delay or a slight miscalculation on a billion-dollar transit hub or a massive industrial facility can result in staggering consequential damages, including lost revenue, extended financing costs, and massive site overhead. As projects become more ambitious and complex, the potential for a catastrophic financial loss increases, making it more likely that a single professional liability claim will reach or exceed the limits of a standard insurance policy. This shift toward larger project scopes has fundamentally altered the risk profile for designers and engineers, as the stakes for every decision are now measured in hundreds of millions of dollars.
Social Inflation and the Rise of Nuclear Verdicts
Beyond the measurable impact of economic inflation, the professional services industry is currently grappling with the phenomenon known as “social inflation.” This term describes the rising cost of insurance claims resulting from broader societal shifts, including a more litigious culture, an expansion of the legal definitions of liability, and a general public distrust of large corporate entities. In the United States, social inflation has been outpacing general economic inflation for several years, driven by a legal environment that increasingly favors plaintiffs and views insurance policies as bottomless pools of capital for compensation. This trend is particularly evident in the construction and engineering sectors, where juries are more inclined to award massive damages based on emotional appeals rather than strictly technical evidence of negligence. This shift in the judicial climate has created a landscape where the predictability of legal outcomes has diminished, forcing firms and their insurers to consider higher settlement amounts to avoid the uncertainty of a trial.
The most extreme manifestation of social inflation is the “nuclear verdict,” defined as a jury award that exceeds $10 million. These massive awards have become increasingly common in major construction markets such as Texas, New York, Florida, and California. While only a small fraction of professional liability cases actually reach a jury trial, the mere threat of a nuclear verdict creates a “halo effect” that pulls all out-of-court settlements upward. Defense attorneys and insurance carriers, fearful of a runaway jury award that could bankrupt a firm or exhaust a policy, are often pressured to settle for sums that were once considered extraordinary. This environment has effectively reset the benchmark for what constitutes a “fair” settlement. The rise of litigation funding—where third-party investors provide capital to plaintiffs to pursue long-term legal battles—has further fueled this trend, as it allows claimants to hold out for higher payouts rather than settling early, thereby driving up both the defense costs and the final indemnity amounts paid across the industry.
Labor Constraints and Shifting Project Delivery Models
The structural transformation of how projects are designed and built is also contributing to the volatility in claim severity. There is a clear trend toward the Design-Build (DB) delivery model, which is expected to account for half of all construction spending by the end of the current decade. While this model offers efficiencies in terms of timeline and cost certainty for the owner, it often blurs the lines of responsibility between the designer of record and the builder. When a dispute arises regarding a project failure or delay, determining whether the fault lies with a design error or a construction defect becomes an incredibly complex legal hurdle. This ambiguity frequently leads to protracted litigation where multiple parties spend years and millions of dollars attempting to allocate blame. The resulting “friction costs” add to the severity of the claim, as the professional liability insurer must defend the firm against both the project owner and the cross-claims filed by the general contractor.
Compounding these structural shifts is an acute shortage of qualified labor across the entire architecture, engineering, and construction spectrum. With nearly 300,000 unfilled positions in the construction sector alone, the pressure on existing professional staff is reaching a breaking point. Many firms have reported being forced to decline work or, more dangerously, to operate with leaner teams that are stretched across too many complex projects. This environment increases the probability of fatigue-related errors and limits the time available for rigorous internal quality control and peer review processes. Furthermore, as experienced senior professionals reach retirement age, firms are increasingly relying on less experienced staff to perform critical tasks, which can lead to a higher frequency of technical oversights. When these errors do occur, the lack of experienced oversight often means they are not caught until deep into the construction phase, at which point the cost of rectification has peaked, contributing directly to the trend of rising claim severity.
Infrastructure Cycles and Insurance Market Reactions
The current historic cycle of development, fueled by significant government infrastructure spending, has introduced a new layer of long-term risk for professional firms. Many of the large-scale projects initiated by recent legislation have extremely long lifecycles, meaning that a professional judgment made during the planning phase in 2026 might not be tested or scrutinized until the project is mid-construction in the early 2030s. This extended “tail” of liability exposure means that firms remain legally and financially responsible for decisions made in a vastly different economic or environmental context years prior. For example, a design that meets all current climate and safety standards may be viewed as deficient a decade from now if environmental conditions or building codes shift more rapidly than anticipated. This long-duration exposure makes it difficult for firms to accurately price their risk and ensures that claims arising from these mega-projects will be resolved in an even more expensive future legal environment.
The insurance industry has responded to these compounding factors by implementing more rigorous underwriting standards and maintaining upward pressure on premiums. In the first half of 2026, the direct incurred loss ratio for professional liability reached 65.1%, indicating that the rate increases of previous years have not been sufficient to offset the rapid escalation in claim severity and social inflation. Insurers are now scrutinizing the internal risk management protocols of architectural and engineering firms with unprecedented detail, often requiring proof of robust peer review systems and stringent contract language that limits liability. For professional service providers, this means that obtaining adequate coverage is no longer a simple transactional process but requires a proactive demonstration of risk mitigation. The combination of deteriorating loss ratios and the sheer volatility of large claims suggests that the market will remain challenging for the foreseeable future, as insurers seek to find a new equilibrium in an era where the financial stakes of professional errors have never been higher.
Strategic Frameworks for Navigating the New Risk Environment
The path forward for professional firms required a departure from traditional, reactive risk management in favor of a more proactive, partnership-based approach. Lessons drawn from other sectors, such as healthcare network management, demonstrated that reducing administrative and legal friction was essential for controlling costs. Successful firms implemented strategies focused on administrative efficiency, ensuring that communication between project stakeholders was clear and documented to prevent the “rework” that often fuels litigation. By prioritizing human connection and peer-to-peer collaboration early in the project lifecycle, organizations were able to resolve technical disagreements before they evolved into formal legal disputes. The shift toward “narrower” networks of high-quality sub-consultants and partners allowed firms to ensure that all parties on a project shared the same commitment to quality and risk mitigation, thereby reducing the likelihood of the complex fault-allocation battles that have historically driven up claim severity.
The integration of data transparency and performance benchmarking also played a critical role in stabilizing the professional liability landscape. Firms began using advanced analytics to identify the specific types of projects or contractual arrangements that were most likely to lead to high-severity claims, allowing them to adjust their project selection and fee structures accordingly. This data-driven approach moved the industry away from a culture of surveillance and toward a culture of continuous improvement. Professional service providers who adopted these proactive measures found themselves in a stronger position during insurance renewals, as they could provide tangible evidence of their efforts to reduce both the frequency and the potential cost of errors. Ultimately, the industry learned that while macroeconomic factors like inflation and social trends remained outside their direct control, the internal management of professional standards and contractual clarity provided a necessary buffer against the skyrocketing costs of liability in the modern era.