Small businesses in Kenya currently face a staggering insurance penetration rate of only one percent, leaving the backbone of the economy exposed to financial ruin. This significant vulnerability has prompted a strategic partnership between the Jubilee Group and FSD Africa, aimed at bridging the protection gap through digital innovation. By working with seven specialized insurtech companies from the BimaLab Africa Insurtech Accelerator, these organizations are launching an initiative to protect vulnerable economic segments. This program is a structured attempt to solve a systemic problem where low-income individuals and small enterprises are often one accident away from bankruptcy. The collaboration focuses on an intensive eight-week co-creation phase designed to ensure that new insurance products are technically sound and economically relevant. By late 2026, large-scale pilots will be deployed to test these solutions in real-world scenarios, marking a pivotal shift in how financial risk is managed in the East African landscape.
Specialized Networks and the Democratization of Coverage
The initiative brings together a diverse group of seven insurtech firms, including Dukatech Solutions and Inclusivity Solutions, to modernize the delivery of financial products. These companies were selected based on their proven ability to navigate the complex digital distribution networks of the region, moving insurance away from traditional brick-and-mortar offices. By integrating coverage into mobile platforms, the program ensures that insurance is as accessible as any other digital service for the average consumer. This shift is essential in a market where mobile penetration far exceeds the reach of traditional bank branches. The goal is to create a seamless user experience that fosters trust among populations that have historically been excluded from formal financial systems. As these digital distribution channels become more established, the focus remains on ensuring that the technology is intuitive and that the benefits of coverage are clearly communicated to first-time policyholders across the country.
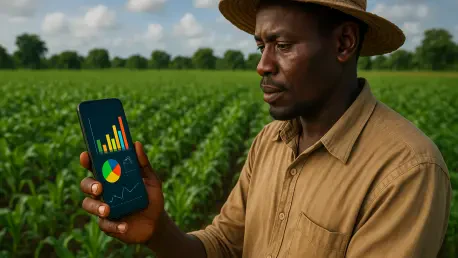
Technological specialization also extends to climate-risk assessment through partnerships with firms such as Ibisa Network and Agrails. These companies provide parametric insurance models that use satellite data to monitor weather patterns and trigger automatic payouts for farmers. Unlike traditional insurance, which requires lengthy claims assessments and manual inspections, parametric triggers allow for rapid financial assistance based on predefined environmental factors like rainfall levels. This speed is critical for small-scale farmers who need immediate capital to recover from drought or excessive rains. By removing the administrative hurdles that typically delay compensation, the initiative provides a more reliable safety net for the agricultural sector, which remains a primary driver of the regional economy. This data-driven approach not only improves the speed of payouts but also lowers the costs associated with managing micro-insurance policies, making them more sustainable for both the provider and the insured.
Embedded Models and Small Business Ecosystems
Embedded insurance serves as a primary pillar of the strategy, integrating protection directly into everyday transactions to reduce the friction of acquisition. By bundling insurance with the purchase of seeds, fertilizers, or digital payment services, the program makes financial security a natural part of a consumer’s routine. This contextual approach means that merchants and farmers do not have to seek out separate insurance products; instead, the coverage is included at the point of sale. Such integration is particularly effective in the informal economy, where small business owners often lack the time or resources to navigate complex financial applications. By making insurance an invisible but essential part of the commercial ecosystem, the partnership aims to normalize the concept of risk management among underserved populations. This strategy also enables the collection of small, frequent premiums that match the irregular cash flows common in these sectors, providing a flexible financial tool that fits the user’s specific economic reality.
The second pillar focuses on building resilience within the Small and Medium-sized Enterprise (SME) ecosystem by aligning insurance products with specific business risks. With SMEs providing the vast majority of jobs in East Africa, protecting these entities is vital for overall economic stability. The program introduces health engagement and wellness models that move beyond reactive compensation to offer proactive support for business owners and their employees. By providing access to preventative care and health services, the initiative helps reduce the long-term risks associated with illness and absenteeism, which can be devastating for small operations. This service-oriented model transforms the perception of insurance from a burdensome expense into a valuable daily utility that enhances the quality of life. The result is a more holistic approach to financial health, where insurance serves as a foundation for growth rather than just a safety net for failure, allowing local businesses to invest in their future with greater confidence and security.
Technological Integration and the Future of Regional Stability
At the core of this technological transformation is J-Hub, the innovation arm of the Jubilee Group, which serves as an incubator for AI-powered solutions. J-Hub provides the necessary testing ground where the agility of insurtech startups meets the institutional expertise and regulatory oversight of a major insurance provider. The integration of Artificial Intelligence is particularly significant for streamlining underwriting and claims processing, which significantly reduces operational overhead. By automating these complex tasks, the program can offer sustainable policies with lower premiums, making them accessible to a much broader demographic. Furthermore, AI helps in analyzing non-traditional data to assess risk more accurately for those without formal credit histories, further expanding the reach of financial services. This synergy between established corporate resources and cutting-edge digital tools is the engine driving the modernization of the sector, ensuring that innovation is both scalable and compliant with regional financial regulations.
The pilots successfully demonstrated that contextual, tech-enabled insurance was the most effective solution for bridging the protection gap in the East African market. Financial institutions recognized that the transition from product-centric to customer-centric ecosystems allowed them to reach millions of previously underserved individuals. Moving forward, the industry prioritized the adoption of open-API platforms to facilitate the further integration of third-party insurtech services into everyday commerce. Regulators also took action by creating sandbox environments that encouraged the development of new parametric models while ensuring robust protection for consumers. These combined efforts resulted in a significant increase in insurance penetration, fostering a more resilient economy where small businesses were better equipped to withstand financial shocks. The initiative proved that by aligning digital innovation with the specific needs of the informal sector, the barriers to financial inclusion were finally dismantled, paving the way for sustained regional growth and stability.