The current fifteen percent employer National Insurance rate on earnings above five thousand pounds remains a significant focal point of budget concerns. That levy already shapes every calculation around hiring, pay awards, and pension generosity, because employers feel it immediately when they
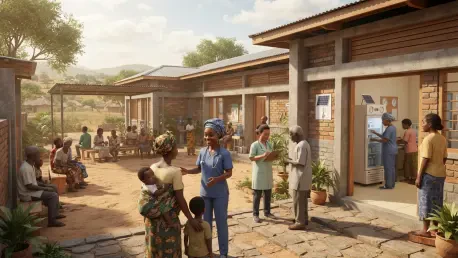
Nigeria’s healthcare landscape is currently undergoing a structural metamorphosis that prioritizes accessibility and financial protection for millions of citizens who previously navigated a fragmented system. This pivot represents a departure from reactive policies toward a proactive, legislatively
Insurance market dynamics, such as soft pricing, have driven firms like Marsh to seek faster organic growth through their expanded consulting and investment arms. The global insurance landscape is currently witnessing a profound identity shift as its most prominent players move away from their
By offering low-cost microinsurance for health and agriculture through the M-Pesa ecosystem, Kenyan insurers have begun winning over a historically skeptical public. This strategic shift addresses a persistent economic paradox where the continent’s growth potential is often overshadowed by a
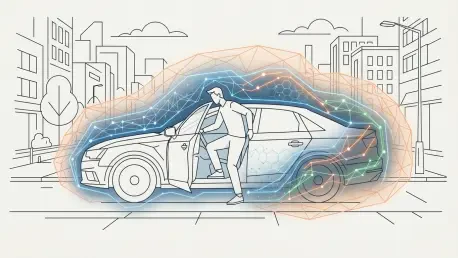
Rideshare insurance operates in three distinct coverage windows, with the highest liability limits only becoming active once a passenger is physically inside the vehicle. For residents of car-free urban centers in 2026, these commercial policy layers represent the only available protection
The first wave of true success in the BCI sector will likely belong to companies that prioritize long-term patient safety over flashy investor-facing narratives. As early 2026 unfolds, China's Brain-Computer Interface (BCI) industry has transitioned from a series of niche laboratory experiments
1 2 3 4 5 6 7 8 9 10 11 12 13 14 15 16 17 18 19 20 21 22 23 24 25 26 27 28 29 30 31 32 33 34 35 36 37 38 39 40 41 42 43 44 45 46 47 48 49 50 51 52 53 54 55 56 57 58 59 60 61 62 63 64 65 66 67 68 69 70 71 72 73 74 75 76 77 78 79 80 81 82 83 84 85 86 87 88 89 90 91 92 93 94 95 96 97 98 99 100 101 102 103 104 105 106 107 108 109 110 111 112 113 114 115 116 117 118 119 120 121 122 123 124 125 126 127 128 129 130 131 132 133 134 135 136 137 138 139 140 141 142 143 144 145 146 147 148 149 150 151 152 153 154 155 156 157 158 159