Strategic acquisitions are now focusing on integrating digital capabilities with risk transfer to bridge the massive protection gap in the global cyber insurance market. This initiative emerges as the global insurance landscape navigates a transformative period defined by the convergence of systemic threats that defy traditional silos. Munich Re’s latest strategic assessments reveal an industry that is no longer managing isolated incidents but is instead grappling with a complex web of interconnected risks. These range from climate-driven environmental disasters to the rapid evolution of digital warfare and persistent inflationary pressures that decouple economic costs from premium rates. In this era of heightened volatility, the necessity for appropriately priced insurance has never been more critical. The current environment demands a move toward sophisticated models that can maintain economic stability during periods of systemic stress, ensuring that reinsurance capital serves as a dependable buffer against the compounding effects of global instability and rapid technological shifts.
Addressing Environmental and Digital Vulnerabilities
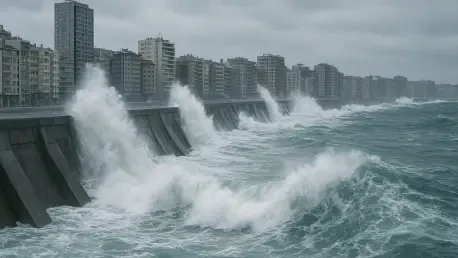
The escalating climate crisis remains the most visible driver of rising insurance losses, particularly within the European market where environmental stressors have reached unprecedented levels. Projections for the mid-2020s suggest a dramatic increase in temperatures and widespread wildfires that threaten the structural integrity of regional economies. These conditions trigger a domino effect that disrupts vital sectors such as agriculture and energy production, proving that environmental shifts have far-reaching consequences beyond simple property damage. Simultaneously, the digital landscape is undergoing a parallel transformation, as the rapid proliferation of advanced technologies creates new vulnerabilities. This convergence of climate and digital risks forces a strategic pivot toward holistic risk management, where insurers must address the physical impacts of a changing planet alongside the intangible but equally devastating threats found within modern digital infrastructure.
The Rising Impact: Secondary Perils and Climate Shifts
A critical shift in loss patterns has emerged, where “non-peak” perils such as localized flooding, hail, and convective storms now account for approximately 70% of insured losses. The intensification of the hydrological cycle means a warmer atmosphere holds significantly more moisture, leading to more frequent heavy rainfall and severe flood events across urban centers. These secondary perils are growing at an accelerating rate, forcing insurers to rethink their traditional focus on large-scale catastrophes in favor of these more frequent, localized events that cumulatively drain capital reserves.
To address these changes, the industry must prioritize adaptation strategies that include investing in physical defenses and more accurate meteorological modeling. As temperatures in France and surrounding nations reach levels significantly above historical averages, the impact on transport infrastructure and energy grids becomes more pronounced. By focusing on these specific climate drivers, reinsurers can better prepare for a future where environmental volatility is the constant baseline rather than the exception. Building such resilience requires a move away from purely historical data toward predictive analytics.
Evolution of Cyber Threats: The Influence of Artificial Intelligence
The digital landscape is currently being reshaped by the proliferation of artificial intelligence and geopolitical instability, which have empowered cybercriminals to execute more sophisticated attacks at scale. AI technologies allow for the automation of complex social engineering and the creation of highly convincing deepfakes, contributing to a significant rise in the total economic costs associated with digital crime. Geopolitical tensions further exacerbate these risks, as state-sponsored actors target interconnected digital systems, creating potential for systemic failures that transcend national borders and industry sectors.
Despite the increasing frequency and severity of these cybercrimes, a massive protection gap persists, with the majority of global companies feeling inadequately covered by existing policies. To combat this, reinsurers are integrating active risk mitigation and technology-enabled services that move beyond simple loss indemnification toward comprehensive prevention. By focusing on real-time threat monitoring and digital defense systems, the sector aims to provide sustainable insurance solutions for an economy dependent on digital infrastructure. This shift ensures that insurance acts as a proactive shield rather than a reactive fix.
Navigating Economic Pressures and Capital Stability
Economic pressures, specifically in the form of persistent inflation, pose a nuanced challenge that requires a more granular understanding than broad headline figures typically provide. In the mid-2020s, the decoupling of economic costs from premium rates has created a landscape where traditional pricing models may no longer be sufficient to ensure long-term profitability. This is particularly evident in sectors where specialized labor and technical components are essential, as the cost of these inputs often rises independently of the general consumer price index. Insurers are now tasked with identifying these specific cost drivers to maintain a balanced portfolio in a volatile market.
Furthermore, the stability of the global economy depends on the ability of the insurance industry to provide dependable capital even during periods of high inflation. This requires a strategic focus on data-driven decision-making and a move away from reliance on historical trends that may no longer accurately predict future costs. By navigating these economic pressures with precision, the industry can continue to offer the protection necessary to support global commerce and individual financial security, acting as a stabilizer against shifting macroeconomic tides.
Persistent Inflation: Analyzing the Motor Insurance Paradox
In the motor insurance sector, a stark disparity has developed between the rising costs of claims and the adjustment of premium rates, creating a significant profitability gap. Between 2026 and 2028, the cost for vehicle spare parts and specialized medical expenses is projected to rise much faster than average premiums in several major markets. This imbalance is driven by the increasing complexity of modern vehicles and the rising cost of healthcare, which forces insurers to utilize more sophisticated tools to distinguish between various inflationary trends and to price risks with greater accuracy across diverse regions.
To combat these challenges, the industry is increasingly turning to AI-driven insurance analytics platforms for data augmentation and portfolio steering. These advanced tools allow for a more precise analysis of claim frequency and severity, enabling insurers to adjust their strategies in real-time. By utilizing high-resolution data, companies can better align their premium structures with the actual cost of repairs and medical care, ensuring that they remain solvent while providing essential coverage to motorists worldwide. This level of technical integration is becoming the standard for maintaining financial health in a high-cost environment.
Reinsurance Foundations: The Role of Traditional Capital
In an era of market volatility, traditional reinsurance capital solidified its role as the primary cornerstone of global capacity, offering the financial strength necessary to provide reliability across market cycles. This capital remained distinct from more transient alternative sources, such as catastrophe bonds, by maintaining the independence required to hold significant risk on balance sheets without excessive reliance on retrocession. Reinsurers prioritized expertise-driven pricing and incorporated forward-looking climate and cyber models to replace outdated historical data, ensuring that premiums remained sufficient to cover systemic losses during periods of stress.
The successful integration of technological platforms and active risk mitigation moved the industry toward a more proactive stance. Stakeholders invested heavily in physical and digital defenses, which successfully reduced the overall impact of secondary perils and cyberattacks before they reached a crisis point. These strategic actions established a more stable foundation for the global economy, demonstrating that dependable capital and innovative risk management were the most effective tools for navigating a landscape defined by compounding global threats. By aligning capital with advanced modeling, the sector secured its position as a vital guardian of economic continuity.