The ability to dictate specific system permissions ensures that human oversight remains the final authority in the management of business-critical events. This fundamental principle is at the heart of Sureify's aiCONNECT, a platform designed to bridge the gap between static legacy data and dynamic
Global investment firms like Brookfield and Athora are injecting fresh capital into the UK market through high-profile acquisitions of established insurance groups. This surge in institutional interest has propelled the bulk annuity sector into a period of remarkable stability and expansion, where
Traditional insurance claim reporting often relies on static data-entry scripts that struggle to capture the nuance of a customer's personal description of an incident. The move toward Agentic First Notice of Loss (FNOL) represents a paradigm shift for Duck Creek Technologies, moving away from
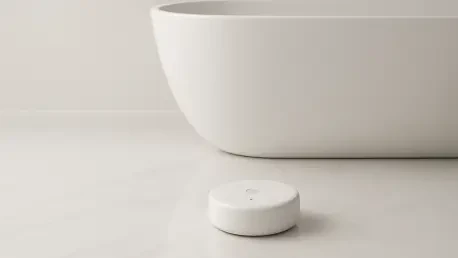
The silent threat of a burst pipe in a high-value property does not care about the fluctuating economic indices or the competitive appetites of modern insurance carriers. A luxurious estate may sit atop a mountain of sophisticated architecture, yet its primary vulnerability often lies in the
Under the proposed framework, insurance companies must ensure that customer mobile numbers match official VAHAN registry records to improve data integrity. This initiative by the Insurance Regulatory and Development Authority of India (IRDAI) is designed to create a more transparent and
Dakar-based Djolof Assur SA has positioned itself as the first entirely digital insurance advisor to meet the evolving expectations of a connected Senegalese workforce. This transformation is not merely a reaction to global trends but a deliberate response to a demographic that increasingly manages
1 2 3 4 5 6 7 8 9 10 11 12 13 14 15 16 17 18 19 20 21 22 23 24 25 26 27 28 29 30 31 32 33 34 35 36 37 38 39 40 41 42 43 44 45 46 47 48 49 50 51 52 53 54 55 56 57 58 59 60 61 62 63 64 65 66 67 68 69 70 71 72 73 74 75 76 77 78 79 80 81 82 83 84 85 86 87 88 89 90 91 92 93 94 95 96 97 98 99 100 101 102 103 104 105 106 107 108 109